Roth IRA vs Traditional IRA: Which Retirement Account Is Better in 2026?
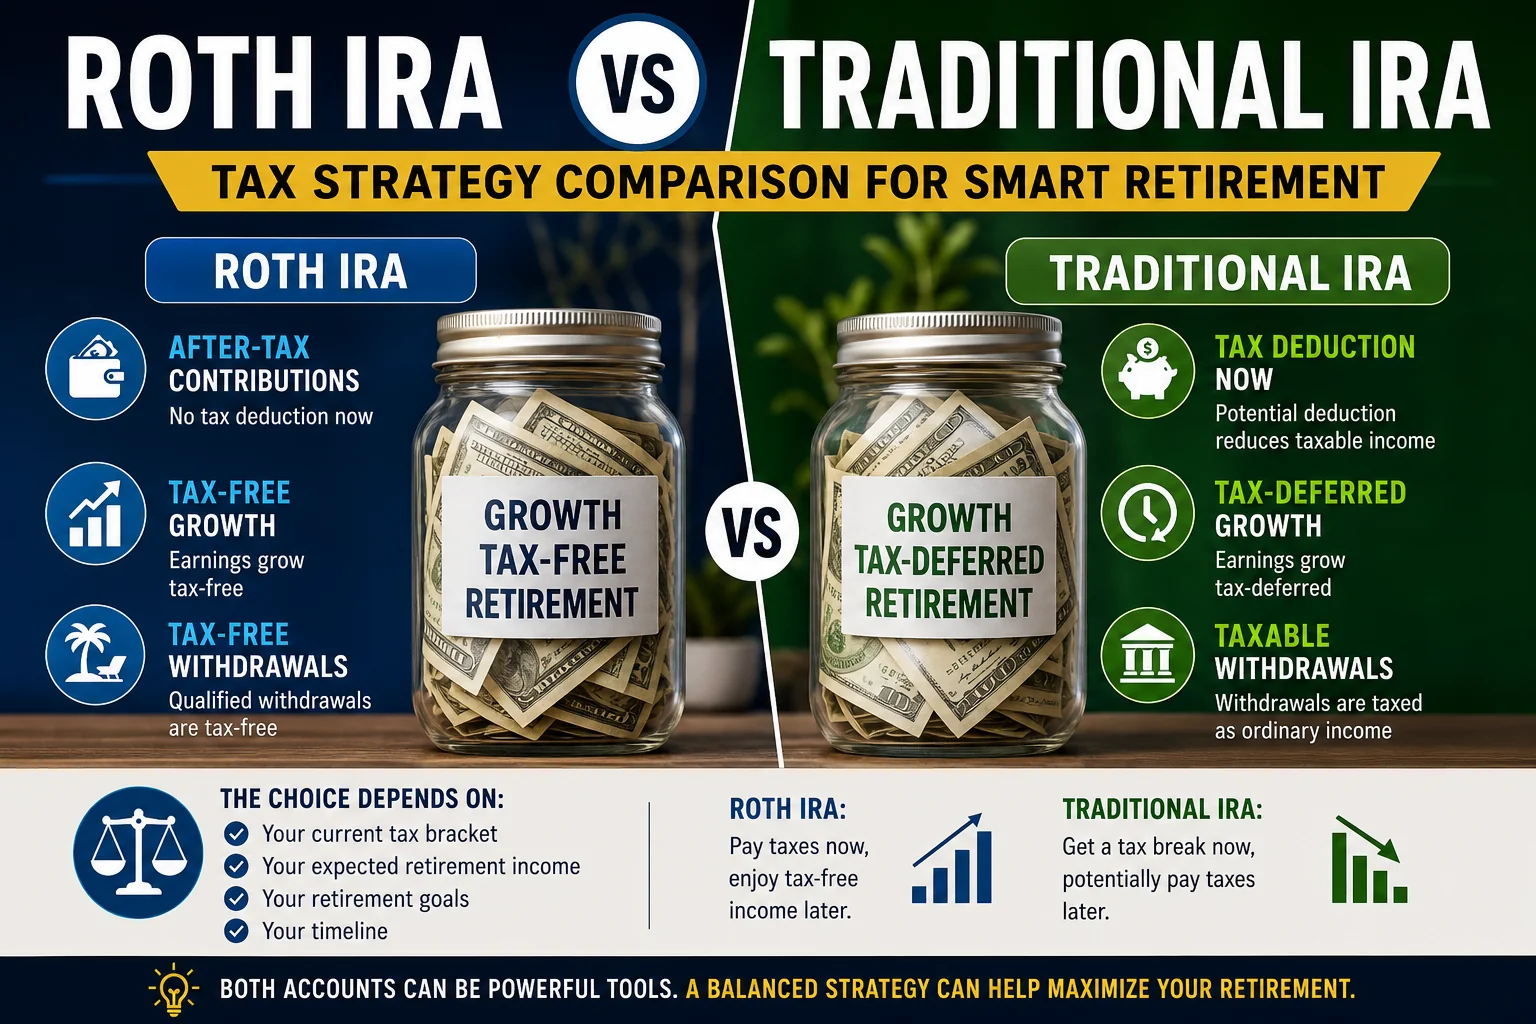
Choosing between a Roth IRA vs Traditional IRA is primarily a decision about when you pay taxes and how much of your retirement savings you may ultimately keep after taxes.
A Traditional IRA may offer an upfront tax deduction if you qualify. Investments can grow tax-deferred, but taxable withdrawals generally count as ordinary income. A Roth IRA is funded with after-tax money, and qualified withdrawals can be tax-free under federal rules.
Neither account automatically produces better investment returns. Both can hold similar investments, including stocks, bonds, mutual funds, and exchange-traded funds (ETFs). The difference lies in the tax treatment.
For 2026, the combined annual contribution limit for Traditional and Roth IRAs is $7,500, increasing to $8,600 for individuals age 50 or older. Your contribution cannot exceed your eligible taxable compensation when that amount is lower. The limit is shared across your Traditional and Roth IRAs, not provided separately to each account.
The right choice depends on:
- Your current marginal federal income-tax rate.
- Whether a Traditional IRA contribution is deductible.
- Your eligibility for a direct Roth IRA contribution.
- Your expected taxable income during retirement.
- Your workplace retirement plan.
- Your investment time horizon.
- Your withdrawal and estate-planning needs.
- State taxes and future changes in tax law.
This guide explains the differences using 2026 U.S. rules, documented historical cases, and transparent calculations. Hypothetical calculations are identified as illustrations rather than presented as real investor experiences.
What Is an IRA?
IRA stands for Individual Retirement Arrangement, commonly called an Individual Retirement Account.
An IRA is a tax-advantaged account designed to help eligible individuals save for retirement. Depending on the provider and account rules, it may hold investments such as:
- Individual stocks.
- Bonds.
- Index funds.
- Exchange-traded funds.
- Mutual funds.
- Certificates of deposit and other permitted investments.
An important distinction is that the IRA is the account, not the investment.
For example, an S&P 500 index fund held inside a Roth IRA remains an index fund. The Roth IRA determines the tax treatment of the account’s contributions, growth, and distributions.
The two principal account types discussed here are Traditional IRAs and Roth IRAs. Both have eligibility requirements, contribution limits, and specific withdrawal rules.
For broader retirement-planning information, visit The AJ Times Retirement Investing guide.
Understanding the Core Difference Between Roth IRA and Traditional IRA
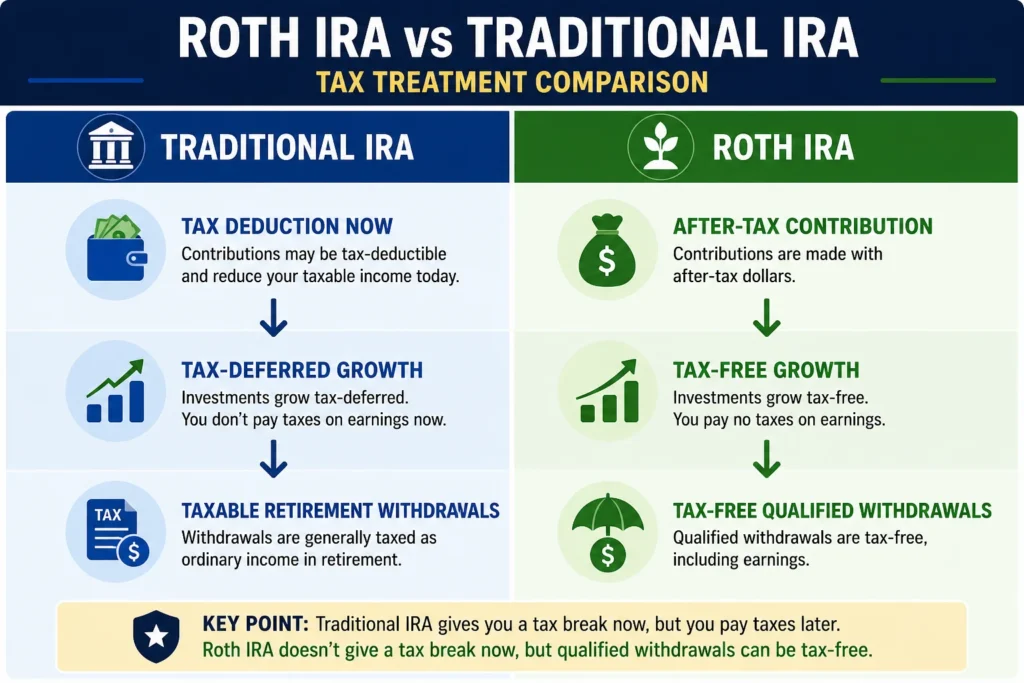
The simplest comparison is the timing of taxation.
When do you want to pay taxes?
Traditional IRA
Potential tax deduction today → tax-deferred investment growth → generally taxable withdrawals later.
A qualifying contribution may reduce current taxable income. Later, distributions of untaxed money are generally included in taxable income.
Roth IRA
After-tax contribution today → investment growth → potentially tax-free qualified withdrawals later.
A Roth contribution generally does not produce a current federal income-tax deduction. Its potential advantage is that qualified distributions can be excluded from federal taxable income.
The better option depends partly on the relationship between your tax rate when contributing and your tax rate when withdrawing.
However, this is not the only consideration. Eligibility, account fees, contribution consistency, required minimum distributions, and access to other retirement plans can also influence the decision.
What Is a Traditional IRA?
A Traditional IRA is a retirement account in which contributions may be deductible under IRS rules.
The deduction is not automatic. Your income, filing status, and participation in an employer-sponsored retirement plan can affect whether you qualify for a full deduction, a partial deduction, or no deduction.
For 2026, the Traditional IRA deduction phase-out for a single taxpayer covered by a workplace retirement plan is $81,000–$91,000 in modified adjusted gross income (MAGI). For a married couple filing jointly when the contributing spouse is covered by a workplace plan, the range is $129,000–$149,000.
Different rules apply when neither spouse is covered by a workplace plan or when one spouse is covered and the other is not.
These thresholds concern the deduction, not a blanket prohibition on making a Traditional IRA contribution. A person may be able to contribute without qualifying for a deduction.
How Traditional IRA Works
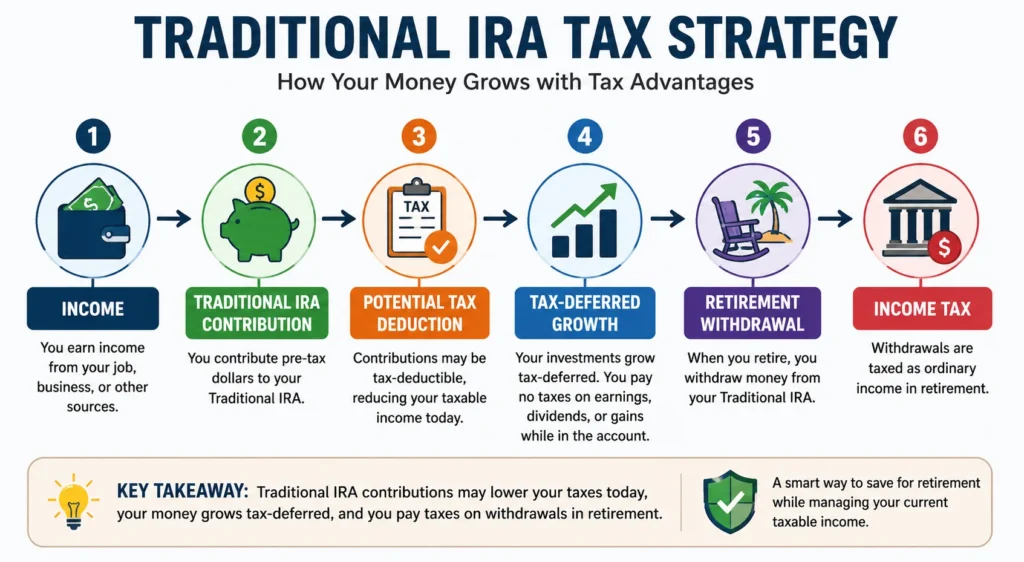
The general process is:
Earn eligible compensation → contribute → claim a deduction if eligible → invest → allow tax-deferred growth → pay applicable tax on withdrawals.
When a contribution is deductible, it can reduce taxable income for the relevant year. Investment earnings generally are not subject to annual federal income tax inside the account.
When money is withdrawn, the taxable portion is generally included in ordinary income. If the account contains nondeductible contributions, part of a distribution may be nontaxable under the applicable basis rules.
Keeping accurate contribution and tax records is therefore important. Form 8606 may be required for nondeductible contributions and certain distributions.
Key Features of Traditional IRA
1. Tax Deduction
An eligible contribution may reduce current taxable income.
The potential tax benefit depends on the amount deductible and the tax rates that apply to the deduction. A deduction is not the same as a tax credit: it generally reduces the amount of income subject to tax rather than reducing the tax bill dollar for dollar.
2. Tax-Deferred Growth
Investments inside a Traditional IRA generally grow without annual federal income taxation of the account’s investment earnings.
Tax deferral can allow more money to remain invested, although fees, investment performance, and the eventual tax treatment of withdrawals still matter.
3. Taxable Withdrawals
Distributions from a Traditional IRA are generally taxable to the extent the money has not already been taxed.
The actual result depends on the account’s contribution history and applicable rules. Nondeductible contributions can create a tax basis that affects the taxable portion.
4. Required Minimum Distributions (RMDs)
Traditional IRA owners generally must begin required minimum distributions at age 73 under current rules.
The first RMD can generally be delayed until April 1 of the year after the year you turn 73. Doing so may mean taking two taxable RMDs in that following calendar year, because the next annual distribution is generally due by December 31.
RMDs should be included in retirement-income and tax planning.
Advantages of Traditional IRA
Immediate Tax Savings
If your contribution is deductible, it may reduce current taxable income. This can be valuable when the deduction offsets income taxed at a relatively high marginal rate.
Useful During Peak Earning Years
Someone earning more during working years than during retirement may find an upfront deduction attractive, provided they qualify.
However, a high salary alone does not guarantee deductibility. MAGI and workplace-plan coverage must be checked.
Potentially Lower Retirement Tax Rate
If taxable income is lower during retirement, withdrawals may be taxed at lower marginal rates than the income offset by the original deduction.
This outcome is not guaranteed. Pensions, Social Security, investment income, RMDs, other retirement accounts, and future tax laws all influence the result.
Disadvantages of Traditional IRA
Taxes in Retirement
The tax advantage generally defers taxation rather than eliminating it. Withdrawals of previously untaxed money can increase retirement taxable income.
Required Withdrawals
RMD rules can limit the owner’s flexibility over when to take money out, even if the owner does not need the distribution for spending.
Future Tax Uncertainty
The tax rates and income circumstances that will apply decades from now are unknown. Choosing a Traditional IRA involves assumptions about future taxes as well as today’s tax benefit.
What Is a Roth IRA?
A Roth IRA is a retirement account funded with after-tax money.
Contributions generally do not provide a current federal income-tax deduction. Instead, qualified distributions can be tax-free, including eligible investment earnings.
Direct Roth IRA contributions are subject to income-based eligibility rules. The amount you can contribute may be reduced or eliminated as MAGI rises through the applicable phase-out range.
Roth IRAs can be attractive to people who value tax-free qualified withdrawals, long-term flexibility, or the ability to leave assets invested without lifetime RMDs for the original owner.
How Roth IRA Works
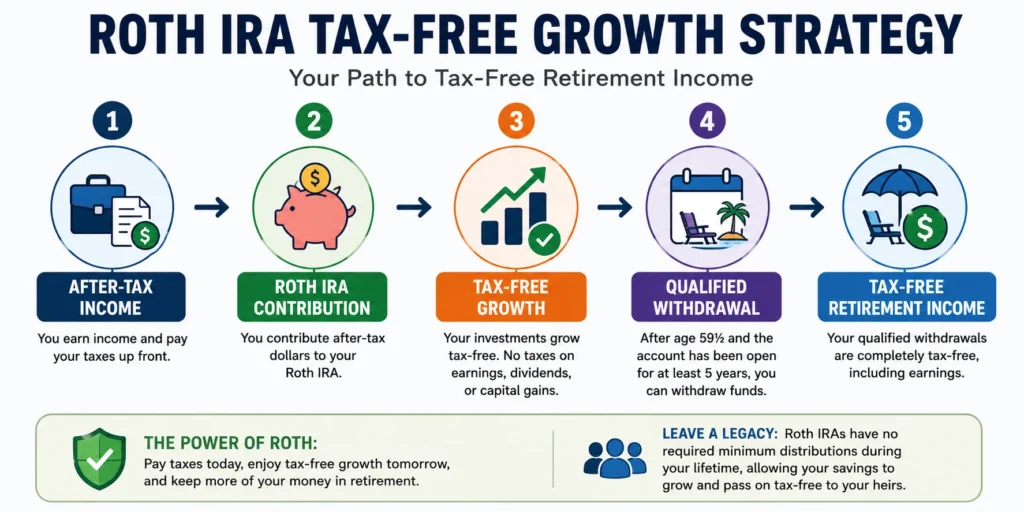
The general process is:
Earn income → contribute after tax → invest → allow growth → take qualified withdrawals under IRS rules.
For a Roth IRA distribution to be qualified, the applicable five-tax-year period must generally be satisfied, along with a qualifying condition such as reaching age 59½. Special rules apply to disability, death, qualified first-home distributions, early withdrawals, and conversions.
Do not assume every withdrawal from a Roth IRA is automatically tax-free. The tax treatment depends on the type of distribution and the account’s history.
Key Features of Roth IRA
1. After-Tax Contributions
Contributions are made with money that has already been subject to applicable taxes. A regular Roth IRA contribution generally does not reduce current federal taxable income.
2. Tax-Free Growth
Investment earnings can be withdrawn free of federal income tax when the distribution meets the requirements for qualified treatment.
3. Tax-Free Retirement Withdrawals
Qualified distributions generally are not included in federal gross income. This can provide valuable flexibility when coordinating withdrawals from several retirement accounts.
4. No Required Minimum Distributions
The original Roth IRA owner generally has no lifetime RMD requirement. Beneficiaries, however, are subject to separate distribution rules.
Advantages of Roth IRA
Tax-Free Retirement Income
Qualified withdrawals can provide retirement spending money without increasing federal taxable income. This can help retirees manage their taxable income alongside other sources of retirement income.
Long-Term Compounding
A long investment horizon allows returns to accumulate over time. The Roth IRA does not make investments earn higher returns, but qualified tax-free withdrawals can improve the eventual after-tax result.
No Lifetime RMDs for the Original Owner
Without lifetime RMDs, the original owner generally has greater control over when to take distributions.
Estate Planning Flexibility
Roth assets may be useful in estate planning. However, beneficiaries have their own distribution requirements, so tax-free treatment should not be confused with unlimited tax-free deferral for heirs.
Disadvantages of Roth IRA
No Immediate Federal Tax Deduction
Roth contributions generally do not reduce current federal taxable income. Someone who needs a current deduction may prefer to investigate a deductible Traditional IRA or other eligible retirement-plan options.
Income Limits Apply
For 2026, the direct Roth IRA contribution phase-out range is $153,000–$168,000 for single and head-of-household filers and $242,000–$252,000 for married couples filing jointly. Special rules apply to married taxpayers filing separately who lived with a spouse during the year.
A taxpayer who cannot contribute directly should not assume that every alternative strategy is automatically appropriate. Roth conversions and Backdoor Roth strategies have different rules and potential tax consequences.
Roth IRA vs Traditional IRA: Side-by-Side Comparison
| Feature | Traditional IRA | Roth IRA |
|---|---|---|
| Contribution tax treatment | May be deductible | Generally not deductible |
| Investment growth | Tax-deferred | Qualified distributions can be tax-free |
| Retirement withdrawals | Taxable to the extent applicable | Qualified distributions generally tax-free |
| Current tax benefit | Possible deduction | Generally no current deduction |
| Lifetime RMDs for original owner | Generally required | Generally not required |
| Income restrictions | Deduction may be restricted | Direct contributions may be phased out |
| Conversion | May be converted to Roth | Can receive eligible conversions |
| Main tax consideration | Potential benefit now | Potential tax-free income later |
Both account types can hold similar investments. The tax treatment, not the account label itself, is the main difference.
2026 IRA Contribution Limits
The combined annual limit for Traditional and Roth IRA contributions in 2026 is:
- $7,500 for people under age 50.
- $8,600 for people age 50 or older, including the $1,100 catch-up contribution.
- A lower amount if eligible taxable compensation is below the applicable limit.
You generally cannot contribute $7,500 to a Roth IRA and another $7,500 to a Traditional IRA as two separate annual limits. The limit applies collectively.
These limits are separate from the contribution limits for employer retirement plans such as 401(k)s.
Always verify your eligibility, compensation, filing status, and the relevant IRS rules before contributing.
2026 Federal Tax Brackets and Why They Matter
Your marginal tax rate is the rate that applies to the next dollar of taxable income within the relevant bracket.
The value of a deductible Traditional IRA contribution depends partly on which marginal tax rates the deduction offsets. A contribution that reduces income taxed at 24% may have a different immediate federal tax effect from one that offsets income taxed at 12%.
The calculation must use taxable income, not salary alone. Filing status, deductions, credits, and other tax-return details affect the result.
The 2026 standard deduction is $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household.
These amounts are federal figures. State income taxes may produce a different outcome.
Roth IRA vs Traditional IRA Calculator: 2026 Example
The following calculations are mathematical illustrations, not real investor case studies, forecasts, or guarantees.
Assume:
- Annual contribution: $7,500.
- Investment period: 30 years.
- Hypothetical annual return: 7%.
- Contributions made at the end of each year.
- No fees or inflation adjustment.
- No tax drag inside the retirement account.
Under these assumptions, investing $7,500 at the end of each year for 30 years at 7% produces approximately $708,456 before considering the account’s tax treatment at withdrawal. At a hypothetical 8% annual return, the result is approximately $849,624.
The calculations show how regular contributions and compounding can affect an account balance. They do not predict market returns, and the results do not establish that either account type will produce a higher after-tax outcome.
What the Traditional IRA deduction could be worth
If a fully deductible $7,500 contribution offsets income taxed at a 22% marginal federal rate, the simplified federal tax reduction would be:
$7,500 × 22% = $1,650
At a 24% marginal rate:
$7,500 × 24% = $1,800
At a 32% marginal rate:
$7,500 × 32% = $2,400
These are simplified calculations, not estimates of a specific taxpayer’s final tax bill. They assume the entire deduction offsets income at the stated marginal rate and exclude state taxes, credits, and other return-specific factors.
An effective retirement calculator should consider filing status, taxable income, eligibility for deductions, expected retirement income, fees, inflation, and withdrawal taxes—not salary alone.
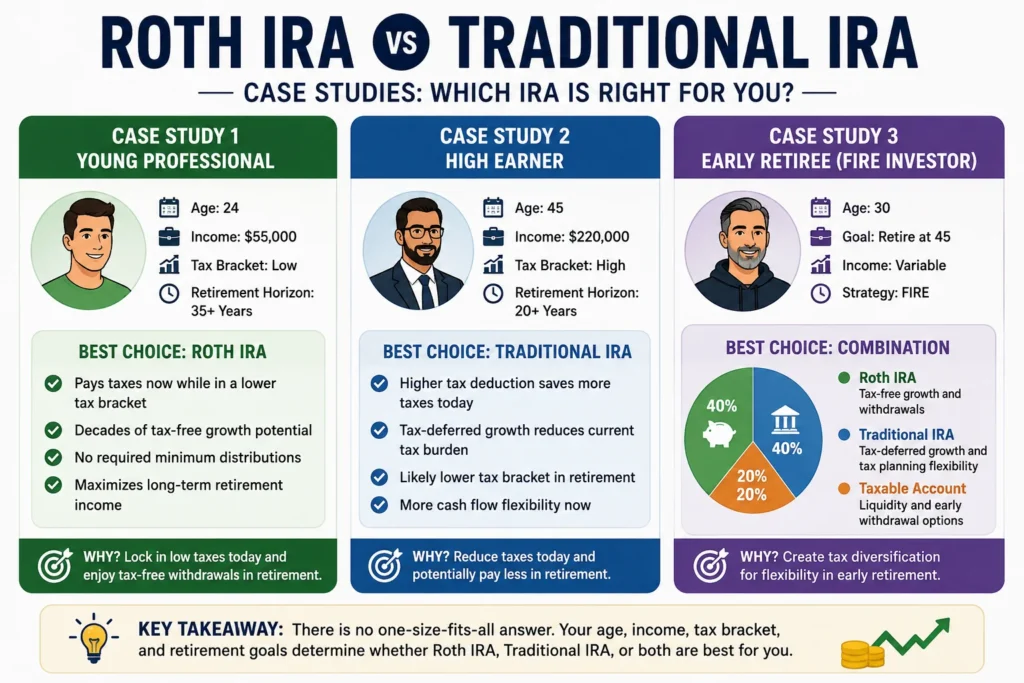
Why Young Investors Often Consider Roth IRA
A long time horizon can make Roth tax treatment attractive, especially when current taxable income is relatively modest and future earnings may be higher.
However, age by itself does not determine the right account. A young person with high taxable income and a different expected retirement situation may face a different choice from another person of the same age.
The important variables are current tax rate, future tax expectations, contribution eligibility, investment horizon, and retirement spending needs.
Why Higher-Income Investors May Consider Traditional IRA
A higher-income taxpayer may value an upfront deduction if eligible. However, workplace retirement-plan participation and MAGI affect whether a Traditional IRA contribution is deductible.
For 2026, a single taxpayer covered by a workplace plan faces a deduction phase-out range of $81,000–$91,000 in modified AGI.
Therefore, the useful question is not simply whether someone earns a high salary. It is whether a deduction is available, how much it is worth, and how that benefit compares with potential Roth tax benefits later.
Real Documented Case: Peter Thiel’s Roth IRA
A widely reported historical case involves Peter Thiel, a co-founder of PayPal.
A 2021 ProPublica investigation based on IRS data and other records reported that Thiel’s Roth IRA grew from less than $2,000 in 1999 to approximately $5 billion by the end of 2019. The investigation described early purchases of private-company shares and subsequent investment gains that were extraordinary and unavailable to most retirement savers.
ProPublica reported that Thiel purchased 1.7 million PayPal-related shares for approximately $1,700 in 1999. The account’s later value reflected exceptional appreciation and unusual investment circumstances.
This is a documented historical case, not a typical Roth IRA outcome. It should not be treated as evidence that ordinary investors can replicate the strategy, access the same transactions, or expect comparable returns.
The relevant lesson is that tax treatment can have a substantial effect when assets appreciate dramatically. The case does not establish that speculative investments are appropriate for retirement savings.
ProPublica also reported that Ted Weschler, an investment manager at Berkshire Hathaway, had a Roth account worth approximately $264.4 million at the end of 2018. Weschler described long-term saving, investment choices, and exceptional luck as factors in his experience.
These figures are historical, not current account balances. Read the original investigation: ProPublica’s report on Peter Thiel and large Roth IRAs.
What the Peter Thiel Case Does – and Does Not – Prove
The case demonstrates the potential scale of tax-free compounding under unusual circumstances. It does not demonstrate that ordinary investors should buy speculative private companies, that Roth IRAs normally generate extraordinary returns, or that every asset is permitted inside an IRA.
For most investors, diversified investments, manageable costs, regular contributions, and a suitable risk level are more practical considerations than attempting to reproduce a billionaire’s investment history.
IRA investment and prohibited-transaction rules still apply. Investors should not assume a transaction is permissible simply because an asset appears to offer large potential returns.
Case Evidence: Growth of Large IRA Accounts
ProPublica also reported historical congressional data showing that more than $15 billion was held in Roth accounts by 156 individuals. Its reporting described a substantial increase in the number of Americans with Traditional and Roth IRAs worth more than $5 million between 2011 and 2019.
These figures describe historical account data and should not be presented as current 2026 totals.
They provide context for the debate about tax-advantaged retirement accounts, but they are not a benchmark for typical retirement savers. Most people should plan around their own contributions, income, investment choices, and spending requirements rather than exceptional account balances.
What Is Tax Diversification?
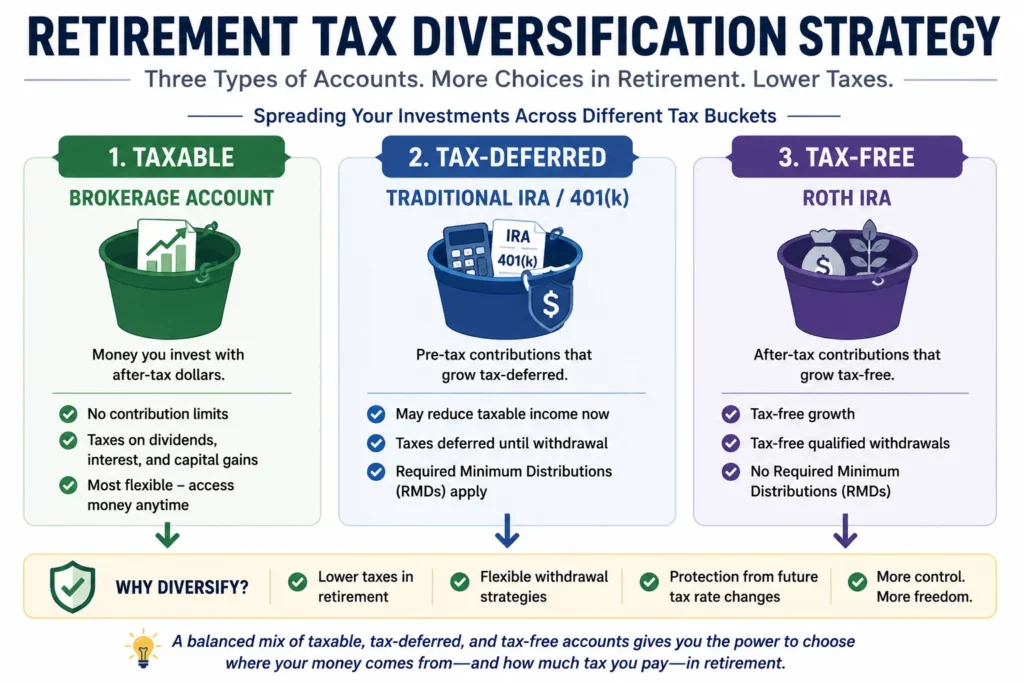
Tax diversification means holding assets with different tax treatments so that retirement income can be managed more flexibly.
Taxable
A regular brokerage account may generate taxable dividends, interest, or realized capital gains under applicable rules.
Tax-Deferred
Traditional IRAs and Traditional 401(k)s generally defer taxation until taxable distributions occur.
Tax-Free
Qualified Roth IRA distributions generally are tax-free under federal rules.
Having more than one tax category can provide flexibility when choosing which assets to use for spending. The right mix depends on the investor’s tax situation, retirement income, and long-term goals.
Explore the The AJ Times Portfolio Strategy guide for more information about diversification.
Understanding Roth Conversion
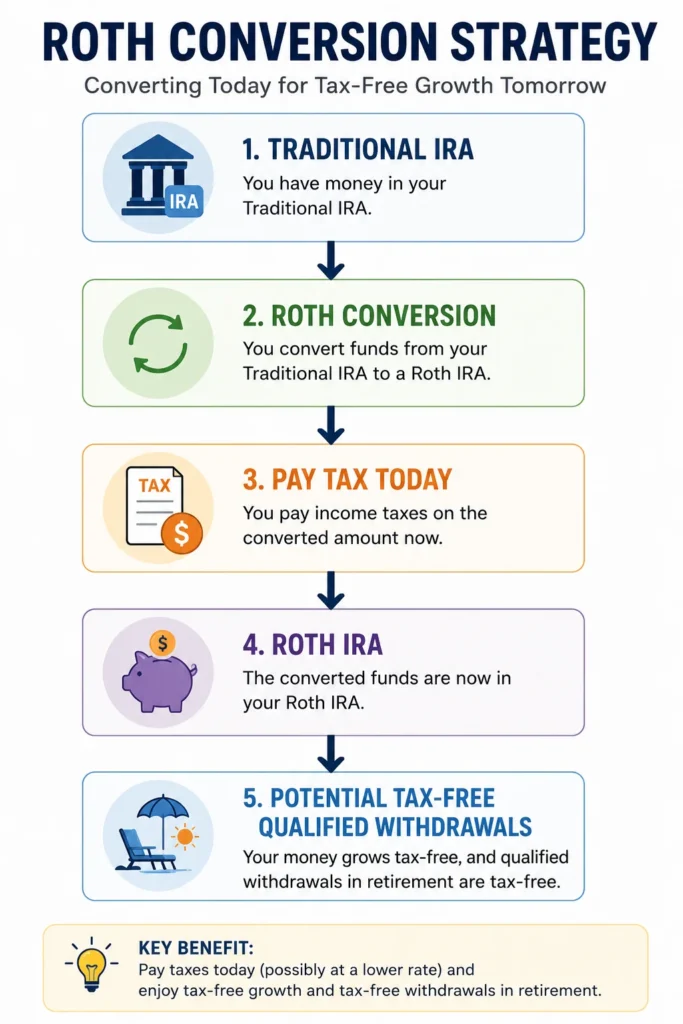
A Roth conversion moves eligible money from a Traditional IRA into a Roth IRA.
The key tax consideration is that untaxed amounts converted are generally included in gross income for the conversion year. A conversion can therefore accelerate taxation in exchange for potential future tax-free qualified distributions.
The decision should account for the amount converted, existing income, available deductions, tax brackets, state taxes, and how the tax bill will be paid.
A conversion is not automatically beneficial simply because Roth withdrawals can be tax-free.
Why Investors Consider Roth Conversions
1. Lower-Income Years
Some people experience years between employment and the start of substantial retirement income when their taxable income is relatively low. A conversion during such a period may have a different tax cost from a conversion during peak earning years.
2. Long-Term Tax-Free Growth
After a conversion, eligible assets can remain invested in the Roth IRA. Future distributions can receive qualified tax-free treatment when applicable rules are met.
3. RMD Planning
Converting part of a Traditional IRA to a Roth IRA can reduce the balance remaining in the Traditional IRA and may affect future RMDs. However, the conversion can create current taxable income, so the trade-off should be evaluated carefully.
Roth Conversion Example
This is a hypothetical calculation illustration, not a real investor case.
Suppose an account owner converts $70,000 from a Traditional IRA to a Roth IRA. If the entire converted amount is untaxed and taxable, it generally increases gross income for that tax year by $70,000.
The actual additional federal tax is not necessarily $70,000 multiplied by one tax rate. It depends on the taxpayer’s other income, deductions, filing status, and marginal tax brackets. State taxes may also apply.
Before proceeding, consider the current tax bill, future tax expectations, conversion timing, and whether the tax can be paid without taking an unnecessary additional withdrawal from retirement assets.
What Is a Backdoor Roth IRA?
A Backdoor Roth is a strategy in which a person makes an eligible Traditional IRA contribution and then converts the money to a Roth IRA.
It is commonly discussed by taxpayers whose income is too high for a direct Roth IRA contribution. However, it is not a special account type, and the tax treatment depends on the details.
One major issue is the pro-rata rule. Other Traditional, SEP, and SIMPLE IRA balances may affect how much of a conversion is taxable. Nondeductible contributions and conversion reporting also need to be handled correctly.
Do not assume that every conversion will be tax-free just because the original contribution was nondeductible. Complex situations should be reviewed with a qualified tax professional.
Importance of Compound Interest
Compound growth occurs when investment returns generate additional returns over time. Regular contributions can increase the amount invested and give the money more time to grow.
Using the 2026 IRA contribution limit as a calculation input, contributing $7,500 at the end of each year for 40 years at a hypothetical 7% annual return would produce approximately $1.50 million. At a hypothetical 8% return, the amount would be approximately $1.94 million.
These figures are mathematical illustrations, not forecasts. They assume a constant return, no fees, and no inflation adjustment. Actual investments can experience losses, and returns vary from year to year.
Also, the $7,500 contribution limit is the 2026 limit, not a guarantee that the same contribution amount will be permitted every year for the next four decades.
Roth IRA and Long-Term Compounding
A Roth IRA does not make investments grow faster. The underlying assets, their performance, investment costs, and the timing of contributions determine investment growth.
The account’s potential tax advantage affects the after-tax result. If a Roth distribution qualifies for tax-free treatment, the owner can retain the distribution without federal income tax on that qualified amount.
A fair comparison between Roth and Traditional accounts should consider both the tax paid on contributions and the tax paid on withdrawals. Comparing account balances alone can give an incomplete picture.
Common Retirement Tax Mistakes
1. Ignoring Future Taxes
An upfront deduction may be valuable, but it is important to account for the tax that may apply to future Traditional IRA withdrawals.
2. Starting Too Late
Delaying contributions reduces the time available for investment growth. Beginning early can help, although contribution consistency and investment risk still matter.
3. Assuming a Traditional IRA Is Always Deductible
Deductibility depends on applicable IRS rules, workplace-plan participation, MAGI, and filing status.
4. Assuming Roth Withdrawals Are Always Tax-Free
Qualified distributions can be tax-free, but early withdrawals and conversions are subject to specific rules.
5. Forgetting the Combined IRA Limit
The annual limit applies collectively to Traditional and Roth IRA contributions. It is not a separate allowance for each account.
6. Ignoring RMDs
Traditional IRA owners generally need to plan for required distributions beginning at the applicable age.
7. Treating a Roth Conversion as Tax-Free
A conversion can create taxable income in the year it occurs. The conversion amount and the account’s tax basis matter.
How Inflation Impacts Retirement Accounts
Inflation reduces purchasing power. A retirement balance that appears large in nominal dollars may buy substantially less in the future.
Retirement planning should therefore account for inflation, investment returns, taxes, healthcare costs, housing, longevity, Social Security, and other retirement income.
The objective is not simply to accumulate a particular account balance. It is to build resources that can support spending after accounting for taxes and changes in the cost of living.
Best Investments Inside an IRA
The IRA is a tax wrapper, not an investment recommendation. The appropriate holdings depend on the investor’s goals, time horizon, risk tolerance, and overall portfolio.
Index Funds
Index funds seek to track a selected market index. They can provide broad market exposure, depending on the index and fund.
ETFs
Exchange-traded funds may offer exposure to stocks, bonds, or other asset classes. Costs, holdings, liquidity, and investment risks vary by fund.
Mutual Funds
Mutual funds pool investor money into a portfolio that may be actively managed or designed to track an index.
Bonds
Bonds may provide income and help diversify a portfolio, but they have interest-rate, credit, and other risks.
Individual Stocks
Individual stocks provide exposure to specific companies. They can offer growth potential but also create company-specific risk and concentration.
An appropriate portfolio is based on an overall investment plan, not on a belief that one account type should always contain the riskiest assets.
Continue learning through The AJ Times’ Stock Market guide and ETFs & Index Funds guide.
Asset Allocation Strategy by Age
Age can help frame retirement planning, but it is not a complete asset-allocation rule.
Age 20–35
A long time horizon may allow an investor to tolerate more short-term volatility, depending on their financial circumstances. Consistent contributions, diversification, and cost awareness are important.
Age 35–50
Investors may need to coordinate retirement contributions with housing costs, family goals, emergency savings, and tax planning. Portfolio risk should reflect the retirement timeline and capacity to absorb losses.
Age 50+
As retirement approaches, withdrawal planning, RMDs, healthcare expenses, tax diversification, and sequence-of-returns risk may become more important. There is no single allocation that is suitable for everyone in this age group.
For more detail, visit The AJ Times’ Portfolio Strategy resources.
Withdrawal Strategies During Retirement
Retirement income may come from taxable brokerage accounts, Traditional IRAs, Roth IRAs, 401(k)s, Social Security, pensions, and other sources.
There is no universal withdrawal order that works for every retiree. Traditional IRA distributions generally increase taxable income, while qualified Roth IRA withdrawals generally do not.
The timing and size of withdrawals can interact with RMDs, Social Security taxation, Medicare-related income thresholds, and other rules. A withdrawal strategy should therefore be reviewed as part of an overall retirement-income plan.
Why Roth IRA Can Be Valuable During Strong Market Growth
When investments appreciate substantially, qualified Roth IRA distributions can allow the owner to receive that growth without federal income tax on the qualified distribution.
However, this does not mean investors should automatically place their riskiest investments in a Roth IRA. Investment selection must still reflect diversification, risk tolerance, time horizon, and the consequences of losses.
The documented Peter Thiel case illustrates an exceptional outcome, not a reasonable return assumption for ordinary investors.
Traditional IRA and Tax Arbitrage
Tax arbitrage, in this context, refers to the potential benefit of paying tax at different rates at different stages of life.
A simplified comparison is:
Higher current marginal tax rate → potentially valuable Traditional IRA deduction.
Compared with:
Lower expected retirement tax rate → potentially lower tax on future Traditional IRA withdrawals.
This strategy can be useful if the assumptions hold. But future tax rates, income sources, and tax laws are uncertain. Compare several scenarios rather than relying on one prediction.
Retirement Planning in 2026
A practical retirement plan considers multiple tax categories, not just the account with the largest balance.
Ask yourself:
- What is my current marginal tax rate?
- Am I eligible for a Traditional IRA deduction?
- Can I contribute directly to a Roth IRA?
- What are my contribution limits for 2026?
- What taxable income might I have in retirement?
- How could RMDs affect my future income?
- Could Roth conversions make sense in a lower-income year?
- Do I have investments outside retirement accounts?
- How might Social Security interact with my taxable income?
- What state tax rules apply to me?
The answers should be based on your own financial situation and updated as the rules or your circumstances change.
Which IRA Is Better for Most People?
There is no universally better account.
A Roth IRA may be attractive when current tax rates are relatively low, future taxable income may be higher, and tax-free qualified retirement income is valuable.
A Traditional IRA may be attractive when a contribution is deductible, the current deduction has meaningful value, and future taxable income may be lower.
Some investors use both account types as part of a broader tax-diversification strategy. Others prioritize a workplace retirement plan or different savings options based on eligibility and financial needs.
The important comparison is the expected after-tax outcome, not simply the account balance.
Beginner-Friendly Retirement Blueprint
Step 1: Build Emergency Savings
Maintain an emergency reserve appropriate for your income, obligations, and circumstances before committing too much cash to investments that may fluctuate in value.
Step 2: Understand Your Employer Retirement Plan
If your employer offers a 401(k) match, understand its eligibility and vesting rules. A match can be an important component of workplace retirement compensation.
For 2026, the general employee 401(k) elective-deferral limit is $24,500, separate from the IRA contribution limit. Additional catch-up rules may apply to eligible participants.
Step 3: Check IRA Eligibility
Review taxable compensation, filing status, modified AGI, and workplace retirement-plan coverage before making a contribution.
Step 4: Compare Tax Timing
Estimate the value of a potential Traditional IRA deduction and compare it with the possible future benefits of qualified Roth distributions. Consider both federal and state taxes.
Step 5: Invest Consistently
Build an investment approach suited to your goals and risk tolerance. Contributions, time, fees, diversification, taxes, and investment performance all influence the outcome.
Frequently Asked Questions (FAQs)
Is Roth IRA better than Traditional IRA?
Neither account is always better. The right choice depends on current tax circumstances, expected retirement income, eligibility, investment horizon, and withdrawal needs.
Can I have both Roth and Traditional IRA?
Yes, if you meet the applicable requirements. The annual contribution limit applies collectively across the two account types. For 2026, the combined limit is $7,500, or $8,600 for people age 50 or older, subject to eligible compensation.
Which IRA grows faster?
Neither account type inherently grows faster. Investment performance depends on the assets held, fees, contributions, and market conditions. The key difference is tax treatment.
Do I pay taxes on Roth IRA withdrawals?
Qualified Roth IRA distributions generally are not included in federal taxable income. The applicable five-year and qualifying-event rules must be satisfied.
What is the biggest advantage of a Roth IRA?
A major potential advantage is tax-free qualified withdrawals, including eligible investment growth.
What is the biggest advantage of a Traditional IRA?
For eligible taxpayers, a key advantage is a possible current-year tax deduction.
What are the 2026 IRA contribution limits?
The combined Traditional and Roth IRA contribution limit is $7,500 for people under 50 and $8,600 for people age 50 or older, subject to the compensation limit.
What are the 2026 Roth IRA income limits?
The phase-out range is $153,000–$168,000 for single and head-of-household filers and $242,000–$252,000 for married couples filing jointly. Special rules apply to married taxpayers filing separately.
Can I convert a Traditional IRA to a Roth IRA?
Generally, yes. Untaxed amounts converted are usually included in gross income for the conversion year. Review the tax consequences before converting.
Does a Roth IRA have required minimum distributions?
The original Roth IRA owner generally has no lifetime RMDs. Beneficiaries are subject to separate distribution rules.
When do Traditional IRA RMDs begin?
Traditional IRA owners generally must begin RMDs at age 73 under current rules, subject to the applicable required-beginning-date rules.
Can I contribute to an IRA if I have a 401(k)?
Having a workplace retirement plan does not automatically prevent IRA contributions. However, workplace-plan coverage and income may affect Traditional IRA deductibility and direct Roth IRA eligibility.
Final Thoughts on Roth IRA vs Traditional IRA
The Roth IRA vs Traditional IRA decision is fundamentally about tax timing, eligibility, and the amount you may ultimately keep after taxes.
A Traditional IRA may provide a deduction today while deferring tax on eligible investment growth until taxable withdrawals occur. A Roth IRA generally uses after-tax contributions and may provide tax-free qualified withdrawals later.
For 2026, the combined IRA contribution limit is $7,500, with a $1,100 catch-up contribution for eligible individuals age 50 or older. Income limits and deduction rules also determine who qualifies for the relevant tax benefits.
The strongest retirement strategy is not necessarily the account with the largest projected balance. It is the strategy that considers contribution eligibility, tax deductions, investment growth, future withdrawals, RMDs, inflation, and the possibility of changes in tax law.
Documented cases involving exceptionally large Roth IRAs show how valuable tax treatment can become under unusual circumstances. They do not represent typical retirement outcomes.
For most investors, the practical objective is to save consistently, choose investments appropriate to their goals, understand the tax rules, diversify where suitable, and review the plan as financial circumstances change.
Financial disclaimer: This article provides general educational information about U.S. retirement accounts and federal tax rules. It is not individualized tax, investment, or financial advice. Tax laws can change, state tax treatment may differ, and investment returns are not guaranteed. Consult a qualified tax or financial professional before making decisions based on your circumstances.
Related Investing Guides
Continue learning with these resources from The AJ Times:
Primary Sources
Verify current retirement-account rules directly with the IRS: