Introduction: Dividend Stocks Explained
Dividend Stocks Explained is a practical guide to understanding how dividend-paying companies distribute profits, how investors calculate potential income, and how to evaluate dividend sustainability before investing. For investors in the United States, United Kingdom, Canada, and Australia, dividend stocks can contribute to long-term wealth building, retirement planning, and portfolio income. However, dividends are not guaranteed, and a high yield does not automatically mean a good investment. Before choosing individual dividend-paying companies, investors should understand fundamental analysis and how to evaluate a company’s financial strength, profitability, and long-term prospects.
This guide explains dividend investing from the basics to advanced analysis, including real company disclosures, worked examples, historical evidence, tax considerations, and ten frequently asked questions. All calculations are illustrative unless explicitly identified as reported company data.
What Are Dividend Stocks? OR (Dividend Stocks Explained)
A dividend is a distribution of money or, in some cases, additional shares that a company pays to eligible shareholders. A shareholder is a person or institution that owns shares in a company. Investors who are new to the stock market can first explore our complete guide to start investing to understand shares, ownership, market risks, and the basics of building an investment portfolio. When you purchase a dividend-paying stock, you acquire partial ownership of that business and may receive a share of its distributions.
Companies can use their profits and cash flow in several ways:
- Reinvest in products, technology, employees, or expansion.
- Repay outstanding debt.
- Repurchase their own shares.
- Maintain cash reserves.
- Distribute money to shareholders through dividends.
Understanding these financial decisions is part of learning how the stock market works, including how companies raise capital, issue shares, and return money to shareholders.
A company does not have to pay dividends simply because it is profitable. Its board generally considers cash flow, future investment requirements, debt obligations, and financial conditions before declaring a distribution.
For example, a mature consumer-goods business might distribute some of its cash to shareholders because it no longer needs to reinvest every dollar to expand. A younger technology business might retain most of its earnings to develop new products.
Neither approach is automatically superior. The right choice depends on the company’s opportunities, financial position, valuation, and the investor’s objectives.
How Dividend Stocks Work
Suppose an investor purchases 100 shares of a company for $50 per share.
- Initial investment: $5,000.
- Annual dividend: $2 per share.
- Shares owned: 100.
- Potential annual dividend income: $200.
The calculation is straightforward:
Annual dividend income = Shares owned × Annual dividend per share
In this example, 100 × $2 = $200 before taxes and any applicable charges.
If the company pays quarterly dividends, the investor might receive four payments of $50 each. Quarterly payments are common among US companies, while payment frequency differs among companies and markets.
The actual payment depends on the company’s declared dividend, the investor’s eligibility on the relevant dates, and whether the dividend is subsequently changed. A company may reduce, suspend, or eliminate its dividend if business conditions deteriorate.
Important dividend dates
- Declaration date: The date the company announces the dividend.
- Ex-dividend date: The date from which a purchaser generally no longer qualifies for the upcoming dividend.
- Record date: The date the company checks its shareholder records to determine eligible recipients.
- Payment date: The date the dividend is distributed.
Investors should verify these dates through company announcements or their brokerage. The US SEC’s Investor.gov explanation of ex-dividend dates explains how eligibility works. Investor
Buying a stock immediately before its ex-dividend date does not create a guaranteed profit. The market price may adjust when the stock begins trading without entitlement to the distribution, and transaction costs and taxes can further affect the result.
10 Powerful Dividend Investing Strategies
1. Understand dividend yield
Dividend yield measures the annual dividend relative to the current share price. It helps investors compare the income a stock offers with the amount required to buy it.
Dividend Yield (%) = (Annual Dividend per Share ÷ Current Share Price) × 100
Example:
Annual dividend per share = $4
Current share price = $100
Dividend yield = ($4 ÷ $100) × 100 = 4%
Illustrative example:
A stock trades at $80 and pays $3.20 annually per share.
- Annual dividend: $3.20.
- Share price: $80.
- Dividend yield: 4%.
A $10,000 investment at the same yield would produce approximately $400 in annual dividends if the dividend and investment value remained unchanged.
Yield changes when the share price or dividend changes. Investors can also examine a company’s valuation using stock analysis techniques before buying shares, rather than relying exclusively on its dividend yield. If the price falls from $80 to $40 while the annual dividend stays at $3.20, the yield rises to 8%. That may look attractive, but the decline could indicate deteriorating business prospects.
Practical lesson: Compare yield with the company’s history, cash flow, debt, and industry peers. Never judge a stock by yield alone.
2. Evaluate the dividend payout ratio
The dividend payout ratio measures the proportion of reported earnings distributed as dividends.
Dividend Payout Ratio (%) = (Dividends / Net Income) x 100
Example: ($200 million / $500 million) x 100 = 40%
Suppose a company earns $500 million and distributes $200 million in dividends. Its earnings-based payout ratio is 40%.
A moderate payout ratio may leave room to invest in the business and absorb temporary difficulties. For a deeper understanding of profitability, financial statements, and business performance, read our guide to fundamental analysis.However, there is no universal safe threshold. A utility, bank, manufacturer, and real estate investment trust (REIT) have different cash-flow patterns and accounting characteristics.
For REITs, analysts often examine funds from operations (FFO) and adjusted funds from operations (AFFO), rather than relying exclusively on conventional earnings, because property depreciation can distort reported profit.
Review the payout ratio alongside cash flow, capital expenditure, debt repayments, and the company’s distribution policy. Investors can verify company earnings, annual reports, and financial disclosures through the SEC EDGAR company filings database.
3. Focus on dividend growth
Dividend growth investing prioritizes companies that can sustainably increase their distributions over time.
Imagine a company pays $1 per share annually and increases that dividend by 5% every year. After ten annual increases, the payment would be approximately $1.63 per share, assuming the growth rate remains constant.
This is a mathematical illustration, not a forecast. Actual dividend increases vary, and companies can freeze or cut payments.
Dividend growth matters because inflation reduces the purchasing power of money. Investors planning for long-term financial independence can also explore our guide to long-term wealth-building strategies.A distribution that rises over time may help offset increasing living costs, but only if its growth is sufficient and the investor’s other expenses are considered. For additional research on dividend sustainability and long-term equity income, consult Morningstar’s analysis of dividends for the long term.
4. Reinvest dividends to compound returns
A dividend reinvestment plan (DRIP) uses dividend payments to purchase additional shares instead of distributing the cash to the investor.
Those additional shares may generate future dividends, which can buy still more shares. Reinvesting distributions is one approach to compounding, and investors should also understand how long-term stock investing strategies can support a disciplined investment plan.This is dividend compounding.
For example, an investor receives $120 in dividends and reinvests it into a diversified holding. The new investment can participate in future gains or losses and may generate additional distributions.
Reinvestment does not guarantee profit. Share prices can fall, dividends can be reduced, and reinvesting into one company can increase concentration risk. Some brokers charge fees or apply specific plan rules. Read the plan’s terms before enrolling. The SEC’s guide to dividend reinvestment plans provides useful background.
5. Avoid high-yield dividend traps
A dividend yield trap occurs when a high yield attracts investors even though the underlying business may be weakening.
Consider an illustrative company whose share price falls from $100 to $30 while its annual dividend remains temporarily at $4. The displayed yield rises from 4% to about 13.3%.
That higher yield may reflect falling earnings, increasing debt, lost customers, or expectations of a dividend cut.
Before investing, ask:
- Is operating cash flow sufficient to fund the dividend?
- Is debt increasing faster than the company’s ability to service it?
- Are revenue and earnings declining?
- Has management explained how it intends to sustain the distribution?
- Is the yield unusually high compared with historical levels and industry peers?
A high yield is a starting point for investigation, not proof of value. Before investing in an unusually high-yielding company, learn how to assess a stock before buying it, including its valuation, earnings, cash flow, and financial risks.
6. Diversify across industries and countries
Diversification means spreading investments across different companies, industries, and, where appropriate, countries so that a single problem does not dominate the portfolio.
A portfolio made up entirely of banks, energy producers, or utilities may appear diversified because it contains several stocks. However, those companies can share similar economic risks.
Consider a hypothetical portfolio spread across healthcare, consumer staples, financials, industrials, utilities, and global businesses. Its income sources may be less dependent on any one industry than those of a portfolio concentrated in a single sector.
International investing introduces additional considerations, including currency movements, foreign withholding taxes, political risk, and different disclosure requirements.
A diversified dividend ETF may simplify the process, but investors should still examine its holdings, sector exposure, fees, and distribution policy. For a broader approach to spreading investment risk across countries and markets, read our global diversification strategy guide.
7. Compare dividends with total returns
Total return combines investment-price changes and income received, including dividends, over a specified period.
Total Return (%) = [(Ending Share Price − Initial Share Price + Dividends Received) ÷ Initial Share Price] × 100
Here:
- Initial Share Price (P₀): The price of the stock when you purchased it.
- Ending Share Price (P₁): The stock’s price at the end of the measurement period.
- Dividends Received (D): The total dividends received per share during that period.
For example, suppose you buy a share for $100, its price rises to $106, and you receive $3 in dividends per share.
Total Return = [($106 − $100 + $3) ÷ $100] × 100 = 9%
The simple formula excludes taxes, transaction costs, and the timing effects of dividend reinvestment.
Suppose a share costs $100, rises to $106, and pays a $3 dividend. Its simple one-year total return is 9%.
Now consider a different stock that pays a larger dividend but falls substantially in price. Its income may not compensate for the capital loss.
Capital appreciation is an increase in the market value of an investment. Investors should also understand how market valuations change over time. Our guide to stock market cycles explains different market phases and their potential effects on investments. For long-term investors, dividend income and capital appreciation should be assessed together rather than treating distributions as free money.
8. Check free cash flow and debt
Free cash flow (FCF) generally measures the cash a company generates after capital expenditure. The precise definition can vary by analyst and reporting context.
A common approximation is:
Free Cash Flow = Operating Cash Flow – Capital Expenditure
Example: $900 million – $300 million = $600 million.
Suppose a company generates $900 million in operating cash flow and spends $300 million on capital expenditure. Its approximate free cash flow is $600 million.
If it pays $250 million in cash dividends, that cash flow appears to cover the distribution. But investors should also consider acquisitions, debt maturities, working-capital needs, and other commitments.
Debt matters because interest and principal obligations compete with dividends for available cash. A business with a rising debt burden and declining cash flow may have less flexibility to maintain distributions during a recession.
9. Use dividend ETFs where appropriate
An exchange-traded fund (ETF) is an investment fund traded on an exchange. A dividend ETF holds a collection of securities selected according to its investment strategy.
Dividend ETFs may focus on high yield, dividend growth, dividend consistency, or international income.
Potential advantages include:
- Exposure to multiple companies through one holding.
- Reduced dependence on a single company’s dividend.
- A rules-based selection process.
- Less need to research every individual company.
Potential disadvantages include management fees, sector concentration, distributions that fluctuate, and limited control over individual holdings.
An ETF is not automatically safe. Review its index methodology, holdings, fees, trading liquidity, tax treatment, and historical drawdowns before investing.
10. Match the strategy to your financial goal
Dividend investing can serve different purposes depending on the investor’s circumstances.
| Investor objective | Approach to evaluate |
|---|---|
| Long-term wealth accumulation | Diversified investments with reinvested distributions |
| Future retirement income | Sustainable dividends plus a broader withdrawal plan |
| Current income | Carefully evaluated income stocks and diversified funds |
| Simplicity | Broad-market or dividend-focused ETFs |
| Inflation-aware planning | Businesses with the capacity to grow earnings and distributions |
A younger investor may prefer reinvestment, while a retiree may need cash distributions to cover expenses. Neither approach removes market risk or guarantees an adequate retirement income.
The appropriate strategy depends on investment horizon, risk tolerance, emergency savings, tax position, and other assets.
Real Dividend Stocks Case Studies
Historical company records help illustrate how dividend policies work in practice. They do not prove that the same companies will deliver similar returns in the future.
Case study 1: Coca-Cola and long-term dividend growth
Coca-Cola – All Brands & Products | Coca-Cola HK
The Coca-Cola Company (NYSE: KO)
Verified company disclosures through 2026
Coca-Cola’s investor disclosures report that the company increased its annual dividend for the 64th consecutive year in February 2026. Its annual dividend was $1.94 per share in 2024 and $2.04 in 2025; the company announced an annualized rate of $2.12 for 2026. The Coca-Cola Company+1
The company operates a large beverage business with established brands and global distribution. Its dividend history illustrates how a mature business can combine shareholder distributions with investment in operations.
Coca-Cola’s annual dividend per share
Reported annual dividends in US dollars for 2019–2025. The 2026 figure is the announced annualized rate, not the final dividend paid for the year.
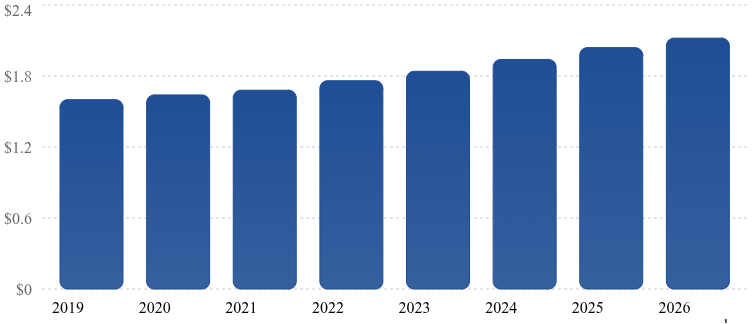
Source: Coca-Cola’s published dividend history and February 2026 announcement.
What investors can learn: A record of dividend increases is useful evidence of past policy, but it is not a guarantee of future increases. Investors still need to examine cash flow, debt, valuation, competitive pressures, and the company’s ability to maintain its distribution. Use the official website: Coca-Cola Investor Relations.
Case study 2: Apple and the balance between growth and dividends
Human Factors Lead Employee at Apple
Apple Inc. (NASDAQ: AAPL)
Apple’s official dividend history shows regular cash dividend payments, including quarterly payments of $0.25 per share in parts of 2024 and $0.26 in several quarters of 2025.
Apple illustrates why dividend yield should not be the only measure of an investment. A company can return some capital to shareholders while retaining substantial resources for research, product development, acquisitions, and other capital-allocation decisions.
An investor who buys a stock primarily for a high current yield may assess Apple differently from an investor who wants exposure to a combination of business growth, share-price appreciation, and a smaller dividend.
What investors can learn: Evaluate the entire business and its expected total return. A lower-yielding company with attractive growth opportunities may be appropriate for some portfolios, while an investor who needs immediate income may have different requirements.
Case study 3: Dividend Aristocrats and the importance of consistency
The S&P 500 Dividend Aristocrats index tracks S&P 500 companies that have increased their dividends in each of at least 25 consecutive years, subject to the index’s eligibility and diversification rules.
This is a rules-based index, not a guarantee that every constituent is financially safe. Companies can face disruption, and index membership can change.
A key distinction is that dividend consistency and dividend yield are different selection criteria. An index that prioritizes a history of increases is not necessarily selecting the highest-yielding stocks.
What investors can learn: A dividend track record can be a useful initial screening tool, but it should be combined with financial analysis, valuation, and diversification. Dividend announcements, stock information and company data.
Dividend Income Example: How Much Can a Portfolio Generate?
Consider a hypothetical investor with a $250,000 portfolio. If the portfolio’s cash yield is 3.5%, its estimated annual dividend income would be $8,750 before taxes and fees, assuming the yield stays constant.
Illustrative Dividend Income Calculator
Estimate annual dividend income before and after an assumed tax rate.
Educational illustration only. Assumes a constant dividend yield and a flat tax rate. Actual dividends, investment values, and taxes can vary. Figures are in US dollars.
Dividend Stocks vs. Growth Stocks
| Feature | Dividend stocks | Growth stocks |
|---|---|---|
| Primary attraction | Cash distributions and possible growth | Potential business and share-price growth |
| Dividend income | May be regular but is not guaranteed | Often low or absent |
| Profit allocation | Some cash may be distributed | More earnings may be reinvested |
| Key risks | Dividend cuts, valuation, weak cash flow | Overvaluation, execution risk, slower growth |
| Suitable objective | Income plus possible appreciation | Long-term capital appreciation |
These categories overlap. A company can pay dividends while growing rapidly, and a dividend-paying company can experience poor growth. Compare actual business characteristics instead of assuming every stock belongs to a rigid category.
Tax on Dividend Stocks in the US, UK, Canada and Australia
Dividend taxation depends on the investor’s residence, account type, income, and the source and classification of the payment.
- United States: Certain qualifying dividends may receive preferential federal tax treatment, subject to eligibility and holding-period rules. The IRS explains these rules in Publication 550.
- United Kingdom: The dividend allowance and applicable rates depend on the tax year and the investor’s circumstances. For 2026–27, HMRC publishes a £500 dividend allowance and the applicable rates on its dividend tax guidance.
- Canada: Eligible dividends from taxable Canadian corporations may qualify for a dividend tax credit. Provincial or territorial rules can affect the final result. See the Canada Revenue Agency’s guidance.
- Australia: Franking credits may reflect Australian company tax paid on profits distributed to shareholders. Eligibility and the treatment of franked and unfranked dividends depend on the investor’s circumstances. See the Australian Taxation Office’s franking-credit guidance.
Foreign investors may also face withholding tax. Tax treaties and foreign-tax-credit rules can change the amount ultimately payable.
Tax rules change, so check official guidance for the relevant tax year and seek qualified advice when necessary.
Major Risks of Dividend Stocks
Dividend Stocks Explained would be incomplete without discussing the risks that can reduce income or damage portfolio value.
Dividend cuts and suspensions
A company may cut its dividend when profits fall, cash flow weakens, debt becomes difficult to service, or management needs to conserve cash. A long record of payments does not prevent a future cut.
Market and valuation risk
A dividend-paying stock can lose value even when its dividend remains unchanged. Paying too high a price for a company can reduce future returns.
Inflation risk
If annual dividends increase by 2% while prices rise by 4%, the dividend’s purchasing power falls. Dividend growth may help, but it does not guarantee inflation protection.
Interest-rate risk
Higher interest rates can make bonds and savings products more attractive relative to dividend stocks. They can also raise borrowing costs for indebted companies. The effect varies by sector and economic conditions.
Concentration and currency risk
Investors who hold only a few dividend stocks may be exposed to company-specific problems. International investments can also rise or fall in value when exchange rates change.
Building a Dividend Portfolio for Long-Term Wealth
A dividend portfolio should reflect the investor’s goals rather than a predetermined yield target.
A sensible research process is to:
- Define whether the primary objective is present income, future income, or total return.
- Decide how much market risk and temporary loss the portfolio can tolerate.
- Compare individual dividend stocks with diversified funds.
- Spread exposure across businesses and industries.
- Reinvest distributions when appropriate for the financial plan.
- Review company fundamentals, dividend announcements, and portfolio concentration periodically.
Do not invest money needed for near-term living expenses in volatile shares simply to earn a higher yield. Emergency savings, debt costs, retirement accounts, and other financial priorities should be considered first.
A practical example of a diversified portfolio
An investor might research companies or funds covering healthcare, consumer staples, financials, industrials, utilities, and international markets. The objective is not to assign equal amounts mechanically to every sector, but to avoid relying excessively on one source of income.
The appropriate allocations depend on the investor’s age, other assets, time horizon, risk tolerance, and income requirements. The following is an educational framework, not a recommended allocation for every investor.
Frequently Asked Questions About Dividend Stocks
1. What are dividend stocks in simple words?
Dividend stocks are shares of companies that distribute some of their money to shareholders. Investors may receive cash payments while also benefiting from potential share-price appreciation. Neither the payments nor the appreciation is guaranteed.
2. How much money do I need to start dividend investing?
There is no universal minimum. The amount depends on the stock price, broker requirements, fractional-share availability, fees, and your financial circumstances. Start by considering affordability, diversification, and your emergency savings rather than targeting a specific dividend amount.
3. Can dividend stocks generate monthly income?
Yes, a portfolio can be structured to receive distributions in different months, but most individual stocks do not necessarily pay monthly. Payment schedules vary, and income is not guaranteed. Monthly income planning may require combining multiple investments or maintaining a cash reserve.
4. Are dividend stocks safer than growth stocks?
Not automatically. Dividend stocks can experience substantial price declines and dividend cuts. Growth stocks carry their own risks, including valuation and business-execution risk. Compare each investment’s financial strength, valuation, and suitability for your objectives.
5. What is a good dividend yield?
There is no single ideal yield for every company or investor. A sustainable 2% yield may be more attractive than an unsustainable 9% yield, depending on valuation, growth, and risk. Compare the yield with the company’s history, industry peers, and cash-flow coverage.
6. Are dividends guaranteed?
No. A company’s board may reduce, suspend, or cancel dividends. Preferred shares may have different contractual terms, but they still carry risks. Review the security’s documentation and the company’s financial condition.
7. Should I reinvest dividends or take them as cash?
Reinvestment may help build wealth over a long horizon. Taking cash may be appropriate when you need income for expenses. Your decision should reflect your financial goals, tax situation, portfolio concentration, and the availability of other income sources.
8. What is the difference between dividend yield and dividend growth?
Dividend yield measures the annual dividend relative to the current share price. Dividend growth measures how the payment changes over time. A high yield does not necessarily imply strong dividend growth, and a growing dividend does not guarantee a high current yield.
9. Do dividend stocks perform well during recessions?
Performance varies. Some companies maintain distributions through recessions, while others reduce them. Share prices may fall even when dividends continue. Financial resilience, industry exposure, debt, and the severity of the downturn all matter.
10. Are dividend ETFs better than individual dividend stocks?
Dividend ETFs can provide diversification and reduce dependence on one company, but they charge fees and may have sector concentration or fluctuating distributions. Individual stocks allow more control but require more research and expose investors to company-specific risk. Neither approach is universally superior.
Conclusion: Are Dividend Stocks Worth Considering?
Dividend stocks can contribute to a long-term investment strategy by providing potential cash income and opportunities for compounding. Their usefulness depends on the quality of the underlying business, the sustainability of its distributions, the price paid, and the investor’s financial objectives.
The central lesson of Dividend Stocks Explained is to look beyond the headline yield. Examine cash flow, debt, payout sustainability, dividend history, valuation, diversification, and taxes before making an investment decision.
A durable dividend strategy is built around financial discipline and a realistic understanding of risk – not promises of effortless passive income.
Editorial disclaimer: This article is for educational purposes only and does not constitute personalized financial, investment, or tax advice. Investments can lose value, and companies may reduce or discontinue dividends. Consider your circumstances and consult a qualified professional where appropriate.