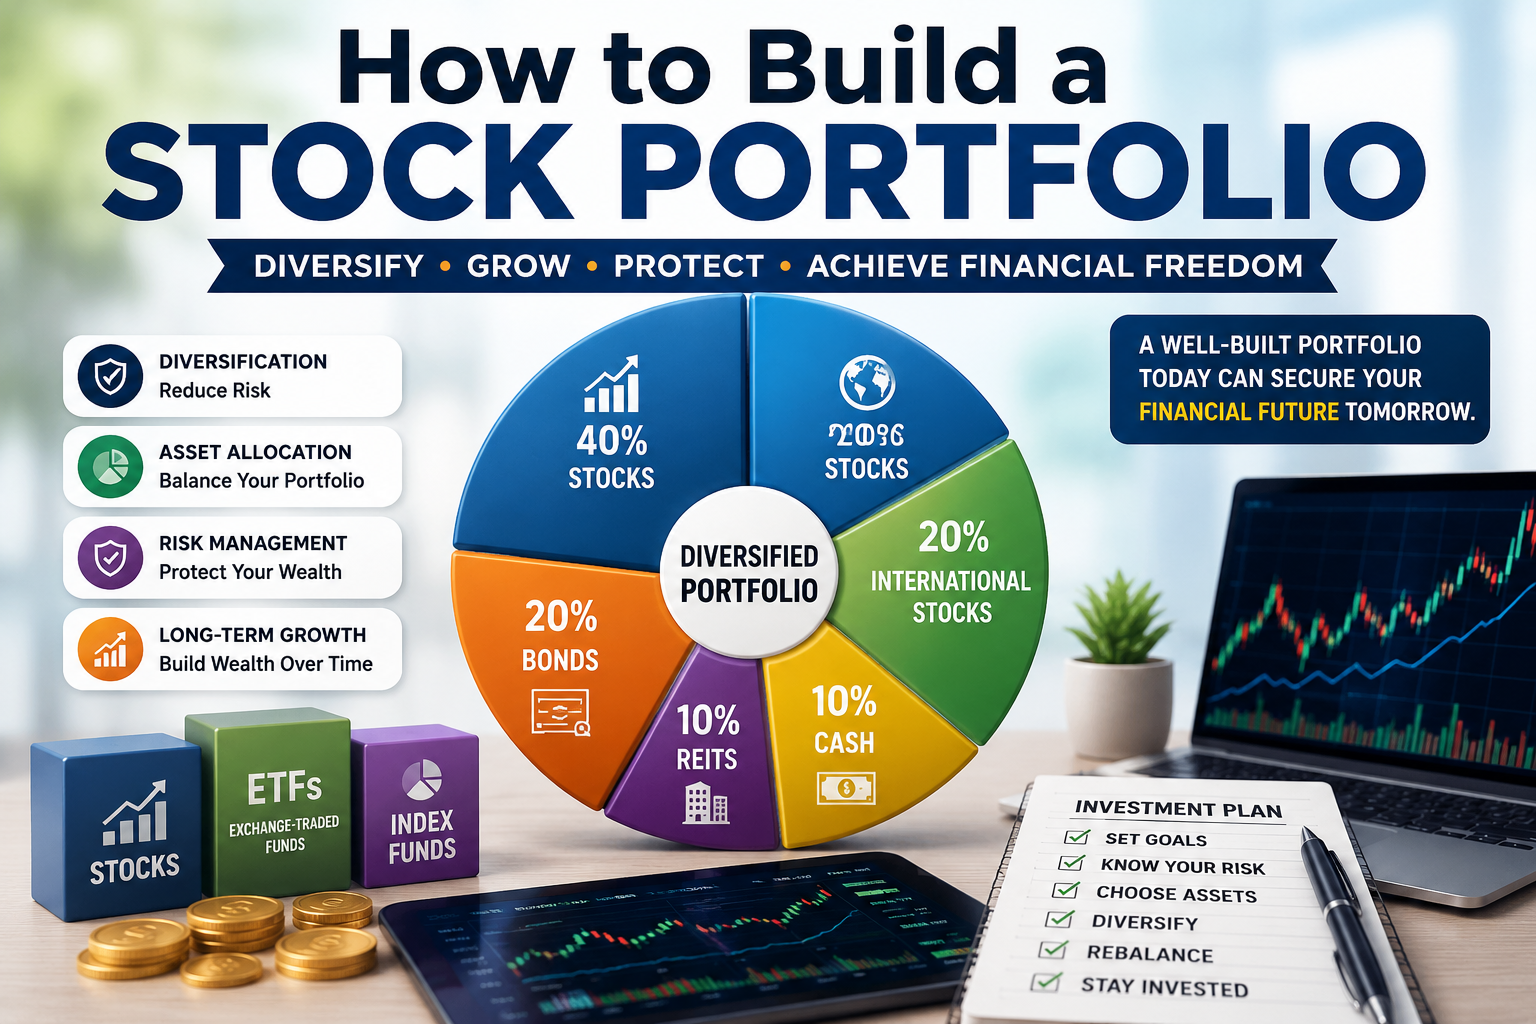
Introduction: How to Build a Stock Portfolio
How to Build a Stock Portfolio is an essential investing skill for people who want to build long-term wealth, manage financial risk, and prepare for retirement. By understanding asset allocation, diversification, investment costs, and risk tolerance, investors can create a portfolio that reflects their financial goals and time horizon.
For investors in the United States, United Kingdom, Canada, and Australia, portfolio construction also involves understanding local investment accounts, tax rules, currency exposure, and retirement systems.
This guide explains how to build a stock portfolio step by step, defines important financial terms in plain English, demonstrates practical calculations, and examines real historical market events to show why diversification and risk management matter.
Important: This article provides general educational information, not individualized financial, investment, or tax advice. All example allocations are illustrative and may not suit every investor.
What Is a Stock Portfolio?
A stock portfolio is a collection of investments held by an individual or institution. It can contain shares in individual companies, stock exchange-traded funds (ETFs), index funds, and other investments selected to meet particular financial objectives.
A stock represents partial ownership of a company. When you buy shares of a publicly traded business, you become a shareholder and may benefit if its share price increases or if it distributes dividends.
A portfolio, by contrast, represents the complete collection of investments you own. It may include stocks alongside bonds, cash, and other assets.
For example, imagine an investor with $20,000 who holds:
- $10,000 in a broad U.S. stock index fund.
- $4,000 in an international stock fund.
- $4,000 in a bond fund.
- $2,000 in cash.
The investor has a diversified investment portfolio with exposure to domestic equities, international equities, bonds, and cash.
The percentages are 50%, 20%, 20%, and 10%, respectively. These figures describe the portfolio’s asset allocation, meaning how its total value is divided among different investment categories.
A portfolio’s value changes as market prices, dividends, interest payments, deposits, and withdrawals change. A carefully constructed portfolio therefore requires periodic review rather than constant trading.
Why Building a Stock Portfolio Matters
A stock portfolio provides a framework for making investment decisions consistently rather than reacting to daily financial news. Understanding how to build a stock portfolio helps investors make informed decisions instead of reacting to market headlines or chasing popular stocks. A well-planned portfolio combines suitable investments, controls unnecessary concentration, and provides a framework for reviewing progress toward long-term financial goals.
Its potential benefits include:
- Long-term growth: Shares can appreciate when businesses expand their earnings and economic value.
- Diversification: Owning different investments can reduce dependence on any single company.
- Dividend income: Some companies distribute part of their profits to shareholders.
- Retirement planning: Long-term investments can help fund future living expenses.
- Inflation protection: Investments that grow faster than inflation may help preserve purchasing power over long periods.
- Financial discipline: A documented investment plan can discourage impulsive decisions.
These benefits are not guaranteed. Stocks can lose substantial value, dividends can be reduced or suspended, and inflation-adjusted returns may be negative for extended periods.
The U.S. Securities and Exchange Commission explains how asset allocation, diversification, investment time horizon, and risk tolerance work together in its Investor.gov guide to asset allocation and diversification.
How to Build a Stock Portfolio Step by Step
When learning how to build a stock portfolio, start with a clear process rather than choosing stocks randomly. Define your financial objectives, assess your ability to handle losses, establish an appropriate asset allocation, and decide how you will diversify and monitor your investments.
Step 1: Define Your Financial Goals
Start by identifying what your money needs to accomplish.
A financial goal is a specific outcome you want to fund through saving and investing. Examples include retirement, a home deposit, education expenses, or long-term wealth accumulation. Start by documenting your financial priorities with our guide to setting investment goals.
Make each goal measurable by identifying its target amount, deadline, and current savings.
For example, an investor may want to build a retirement fund over 25 years. Another investor may need a home deposit in three years.
These goals should not necessarily use the same portfolio. Shares can experience sharp declines over short periods, making them unsuitable as the sole source of money needed for an imminent purchase.
Practical approach: Write down each goal, its expected date, and the amount required. Then decide how much investment risk is appropriate for that specific objective. Investors who want to match their investments to their life stage can also explore our guide to portfolio allocation by age.
Step 2: Understand Your Risk Tolerance and Time Horizon
Risk tolerance means your willingness and ability to accept investment losses and price fluctuations.
Your willingness to take risk is psychological: can you remain calm when investments fall? Your financial ability to take risk depends on factors such as income stability, savings, debts, and when you need the money.
A time horizon is the period between investing and needing the funds. For a deeper comparison of investing timelines, explore long-term vs short-term investing.
An investor saving for retirement in 30 years may be able to tolerate more short-term volatility than someone who needs a deposit in two years. Nevertheless, a long time horizon does not guarantee recovery from every loss or make an unsuitable investment safe.
Consider three broad investor profiles:
- Conservative: Prioritizes stability and accepts less growth potential to reduce volatility.
- Moderate: Balances growth opportunities with investments intended to reduce fluctuations.
- Aggressive: Accepts substantial market volatility in pursuit of higher long-term growth.
To understand how potential returns relate to uncertainty and potential losses, read our guide to risk vs reward investing.
These are general descriptions, not strict categories. An investor’s appropriate portfolio depends on their complete financial circumstances.
Step 3: Build an Emergency Fund Before Investing
An emergency fund is money reserved for unexpected expenses, such as medical bills, urgent repairs, or temporary unemployment.
Without accessible savings, an investor may have to sell shares during a market downturn to pay ordinary expenses. That can turn a temporary market decline into a permanent loss.
A commonly used starting point is three to six months of essential living expenses, although people with irregular income, dependants, or greater financial uncertainty may need more.
For example, someone whose essential expenses are $2,500 per month would need $7,500 to $15,000 for a three-to-six-month reserve.
Keep emergency money in an accessible, relatively stable account appropriate to your country and circumstances. It should not depend on the stock market remaining positive.
Step 4: Choose Your Asset Allocation
Asset allocation determines how your investments are divided among asset classes, such as stocks, bonds, and cash.
Stocks generally offer greater long-term growth potential but can experience substantial losses. High-quality bonds may provide interest income and can sometimes help reduce portfolio volatility, although bonds also carry interest-rate, credit, and inflation risks. Cash offers liquidity but may lose purchasing power when inflation exceeds its return.
Consider this illustrative $10,000 portfolio:
| Asset class | Allocation | Amount |
|---|---|---|
| U.S. stocks | 50% | $5,000 |
| International stocks | 20% | $2,000 |
| Bonds | 20% | $2,000 |
| Cash | 10% | $1,000 |
| Total | 100% | $10,000 |
This example contains 70% stocks and 30% bonds and cash. It is not a universal recommendation; another investor may need a more conservative or more growth-oriented mix.
Choosing the right asset allocation is a central part of how to build a stock portfolio because the mix of stocks, bonds, and cash influences potential returns and overall risk. Review your investment horizon, income needs, and ability to withstand market declines before deciding how much to allocate to each asset class.
A commonly quoted rule of thumb is to subtract your age from 100 to estimate a possible stock allocation. However, this is a simplified heuristic, not a reliable substitute for assessing goals, risk capacity, and investment needs.
The SEC’s asset allocation guide explains why there is no single allocation suitable for every investor.
Step 5: Understand Different Types of Stocks
Knowing what different stock categories mean can help you understand what your portfolio owns and why those investments may behave differently.
Growth Stocks
Growth stocks belong to companies investors expect to expand revenue or earnings rapidly.
These companies may reinvest profits into product development, technology, expansion, or acquisitions rather than paying substantial dividends.
The potential benefit is business growth. The risk is that expectations may already be reflected in a high share price. If results disappoint, the stock may decline sharply.
Value Stocks
Value stocks are shares that appear inexpensive relative to an estimate of their underlying business value.
Investors may compare a company’s share price with earnings, cash flow, assets, and future prospects. A low valuation alone does not prove that a stock is undervalued: the market may be anticipating genuine business problems.
Dividend Stocks
Dividend stocks are shares in companies that distribute some of their earnings or cash to shareholders.
Dividend yield measures annual dividends per share relative to the current share price. A high yield is not automatically attractive because it may reflect a falling price or an unsustainable payout.
Dividends can be reduced or suspended, and total return depends on both price changes and distributions.
Blue-Chip Stocks
Blue-chip stocks are generally associated with large, established companies that have substantial businesses and recognizable brands.
However, size and reputation do not eliminate investment risk. A major company can become overvalued, lose market share, or experience financial difficulties.
Small-Cap and Mid-Cap Stocks
Market capitalization, or market cap, is the market value of a company’s outstanding shares.
It is calculated by multiplying the share price by the number of outstanding shares.
Small-cap companies may have significant growth opportunities but can face greater business, financing, and trading risks. Mid-cap companies fall between small-cap and large-cap categories, although definitions vary by index provider.
These categories describe company size rather than guaranteeing a particular level of safety or performance.
Step 6: Choose Between Individual Stocks and ETFs
An individual stock gives you exposure to one company’s performance. An exchange-traded fund, or ETF, pools investors’ money and holds a collection of investments according to its stated strategy.
A broad-market ETF can provide exposure to hundreds or thousands of securities through a single holding. A narrowly focused ETF may instead concentrate on one sector, theme, or country.
| Feature | Individual stocks | Broad-market ETFs |
|---|---|---|
| Diversification | Requires selecting multiple companies | Can provide broad exposure through one fund |
| Research | Requires company-level analysis | Requires checking the index, holdings, and fund structure |
| Company-specific risk | Can be substantial | Often reduced through multiple holdings |
| Costs | Trading costs may apply | Fund expenses and trading costs may apply |
| Control | Direct choice of each company | Fund follows its investment mandate |
Before choosing your investment approach, read our comparison of stocks vs ETFs to understand the differences in diversification, control, and research requirements.
For investors deciding how to build a stock portfolio efficiently, diversified ETFs can provide exposure to many companies without requiring the selection of every stock individually. Before investing, check each fund’s holdings, expense ratio, investment objective, and geographic exposure to make sure it fits your overall strategy.
Index fund and ETF are not synonyms. An index fund follows an index, while an ETF describes a fund structure traded on an exchange. Some ETFs track indexes; others are actively managed.
Beginners who want a straightforward approach may consider broad, low-cost funds rather than trying to identify dozens of winning stocks. However, fund selection still requires checking fees, diversification, currency exposure, and concentration in major holdings.
For further reading, consult Investor.gov’s introduction to investing.
Step 7: Diversify Across Sectors and Countries
Diversification means spreading investments so that the outcome does not depend excessively on a single company, industry, or market.
A portfolio containing ten technology companies may appear diversified because it owns ten stocks. However, if those companies depend on similar economic conditions, interest rates, or customer spending, their prices may decline together.
Consider exposure to different industries, including:
- Information technology
- Healthcare
- Financial services
- Consumer staples
- Industrials
- Energy
- Utilities
Geographic diversification can also reduce dependence on one country’s economy. Investors may hold domestic and international equities, depending on their goals and circumstances.
Diversification is an important principle in how to build a stock portfolio because spreading investments across companies, industries, and countries can reduce dependence on a single source of risk. However, diversification cannot eliminate losses when financial markets decline broadly.
International investing introduces additional risks, including currency movements, foreign regulations, political uncertainty, and different market structures.
Investors can learn more about geographic diversification in our guide to investing in international stocks.
Important: More holdings do not automatically mean better diversification. Check the underlying holdings of your ETFs to identify overlapping companies and concentrated sector exposure.
Step 8: Research Stocks Before Buying
Before purchasing an individual company, understand how its business makes money, what could cause its earnings to grow, and what might threaten its future.
Start with the following concepts.
Revenue and Earnings
Revenue is the income a company generates from selling goods or services before deducting expenses.
Earnings represent profit after relevant expenses. Rising revenue does not necessarily mean rising profit because operating costs, financing expenses, and taxes can increase.
To understand how company results can influence share prices, read our article on earnings reports and stock prices.
Price-to-Earnings Ratio
The price-to-earnings ratio, or P/E ratio, compares a company’s share price with its earnings per share.
A high P/E ratio can indicate that investors expect substantial future growth, but it may also signal an expensive valuation. A low P/E ratio can indicate value or reflect serious business problems.
Compare companies within relevant industries and investigate the reasons behind valuation differences.
Debt and Cash Flow
Debt creates obligations that must be met even when business conditions weaken. Cash flow helps show whether a company generates cash from operations and can finance its activities.
Review debt levels, interest costs, cash generation, profit margins, and management’s use of capital.
Competitive Advantage
A competitive advantage is a feature that helps a business defend its position against rivals. Examples may include customer loyalty, cost efficiency, patents, distribution networks, or strong switching costs.
These advantages can weaken, so evaluate the evidence rather than relying on a company’s reputation alone.
Use company annual reports, financial statements, regulatory filings, and investor presentations. In the United States, publicly listed companies’ filings can be researched through the SEC’s EDGAR database.
Step 9: Consider a Core-and-Satellite Strategy
A core-and-satellite portfolio places most investments in a diversified core, with a smaller allocation to selected investments.
The core might consist of broad domestic and international index funds. The satellites might include selected individual stocks, small-cap funds, or sector investments.
For illustration, an investor could assign 85% of the equity portion to diversified funds and 15% to individual stocks. This is an example of the structure, not a recommended allocation for every person.
The advantage is that the portfolio does not depend entirely on successful stock picking. The satellite portion can still introduce concentration risk, so establish a maximum allocation before buying speculative investments.
Step 10: Invest Regularly and Understand Dollar-Cost Averaging
Dollar-cost averaging means investing a fixed amount at regular intervals, regardless of short-term price movements.
For example, an investor might contribute $300 monthly to a diversified investment fund.
When the fund price is lower, the contribution purchases more units. When the price is higher, the same contribution purchases fewer units.
A consistent contribution schedule can make it easier to follow your plan for how to build a stock portfolio without trying to predict every market movement. Choose an amount you can sustain after covering essential expenses, maintaining emergency savings, and accounting for investment fees.
This approach can support disciplined investing and reduce the pressure to identify the perfect time to buy. It does not guarantee a profit or protect against a falling market. It can also produce a different outcome from investing an available lump sum immediately when markets subsequently rise.
Automating contributions can help turn investing into a repeatable habit. Before investing, account for transaction charges, fund expenses, emergency savings, and high-interest debt.
Step 11: Understand Compounding
Compounding occurs when investment earnings remain invested and can generate additional earnings.
Suppose an investor places $10,000 into an investment that earns a hypothetical 7% annually, with returns reinvested.
After 20 years, the investment would grow to approximately $38,697 before fees, taxes, and inflation, assuming a constant annual return.
The calculation uses:
Future value = Initial investment × (1 + annual return)<sup>number of years</sup>
This is a mathematical illustration, not a forecast. Actual stock-market returns fluctuate, can be negative, and are not guaranteed to follow a constant rate.
Regular contributions can also affect the result substantially. Time, contribution amounts, fees, taxes, and realized returns all influence the final portfolio value.
Step 12: Rebalance Your Portfolio
Rebalancing means bringing a portfolio back toward its intended asset allocation when market movements cause the proportions to drift.
Imagine a portfolio initially holding 60% stocks and 40% bonds. If stocks rise faster than bonds, the portfolio might become 70% stocks and 30% bonds. Its risk profile may now differ from the investor’s original plan.
Rebalancing can involve directing new contributions toward underweighted assets or selling some overweighted holdings to buy others.
Investors commonly review allocations on a schedule or when predetermined thresholds are reached. Consider transaction costs and tax consequences before selling investments.
The SEC’s guide to asset allocation and diversification discusses why rebalancing helps keep investments aligned with an investor’s goals.
Step 13: Monitor Portfolio Risk
Portfolio risk includes several distinct threats.
- Market risk: The possibility that broad market declines reduce investment values.
- Company-specific risk: Losses caused by company problems, such as weak management or declining sales.
- Inflation risk: The possibility that rising prices reduce the purchasing power of investment returns.
- Interest-rate risk: Changes in interest rates can affect share valuations and bond prices.
- Currency risk: Exchange-rate movements can change the home-currency value of international investments.
- Liquidity risk: The risk that an investment cannot be sold quickly at a reasonable price.
- Concentration risk: Excessive exposure to one company, sector, country, or investment theme.
A portfolio should be evaluated as a whole. Two investments that appear different may react similarly to the same economic shock.
Avoid judging risk only by recent returns or a stock’s reputation. Consider how much you could lose, whether you could tolerate that loss, and whether the money will still be available when needed.
For further reading, consult FINRA investor education.
Step 14: Measure Portfolio Performance
Performance metrics help explain how a portfolio is behaving, but no single number provides a complete picture.
Return on Investment
Return on investment, or ROI, compares an investment’s gain or loss with its initial cost.
For example, an investment bought for $1,000 and later valued at $1,100 has a 10% price gain, excluding dividends, fees, and taxes.
Total Return
Total return accounts for both price changes and income such as dividends, assuming the calculation handles reinvestment consistently.
It is more informative than looking at share-price appreciation alone.
Volatility
Volatility measures the degree to which investment returns fluctuate. Higher volatility means returns have historically varied more, although volatility alone does not describe every form of risk.
Beta
Beta estimates how sensitively a stock or portfolio has historically moved relative to a chosen market benchmark. A beta above 1 indicates greater historical sensitivity to benchmark movements; below 1 indicates lower sensitivity.
Beta is based on historical data and may change over time. It does not guarantee how an investment will behave in a future crisis.
Expense Ratio
An expense ratio expresses a fund’s annual operating expenses as a percentage of its assets. Lower expenses can leave more of the investment return with the investor, all else being equal.
When comparing performance, consider the benchmark, investment period, risk level, fees, taxes, and whether dividends are included.
Step 15: Consider Taxes and Investment Fees
Taxes can materially affect the amount of investment return you keep. Account rules vary by country, and eligibility and contribution limits can change.
United States: Investors may consider employer-sponsored 401(k) plans and eligible Individual Retirement Accounts (IRAs). Traditional and Roth accounts have different tax treatments.
United Kingdom: Individual Savings Accounts (ISAs) and Self-Invested Personal Pensions (SIPPs) may provide tax advantages subject to applicable rules.
Canada: Tax-Free Savings Accounts (TFSAs) and Registered Retirement Savings Plans (RRSPs) have different contribution and withdrawal rules.
Australia: Superannuation is a central retirement-saving structure, with tax treatment and access rules that differ from ordinary brokerage investments.
Also consider brokerage commissions, bid-ask spreads, fund expenses, foreign-exchange charges, and potential account fees. Even small recurring fund expenses can affect long-term outcomes, so explore our guide to expense ratios and long-term returns.
A low-cost investment is not automatically the best choice, but unnecessary expenses can reduce the amount that compounds over time. Check current government guidance or consult a qualified local tax professional for country-specific decisions.
Real Historical Case Studies: Lessons for Building a Stock Portfolio
Historical events demonstrate how portfolio construction can influence outcomes. They do not establish that a particular strategy will always outperform.
Case Study 1: The Dot-Com Bubble, 2000–2002
During the late 1990s, enthusiasm for internet and technology businesses helped drive valuations higher. Some investors purchased shares based on optimistic growth expectations without adequately examining profitability, cash flow, or price.
When the technology bubble burst, many technology shares suffered severe declines. The Nasdaq Composite fell approximately 78% from its March 2000 peak to its October 2002 low, illustrating the damage that can occur in a concentrated market segment.
What investors can learn:
- A popular industry is not necessarily a good investment at every price.
- Revenue growth does not guarantee future profitability.
- Concentrating a portfolio in one theme can amplify losses.
- Valuation, diversification, and financial strength deserve attention before purchase.
A broad portfolio can reduce dependence on one sector, although diversified stock portfolios can still experience significant declines during broad bear markets.
Historical context: S&P Global’s discussion of the technology bust.
Case Study 2: The Global Financial Crisis, 2007–2009
The global financial crisis followed problems in housing finance and credit markets. Financial institutions faced severe stress, credit conditions tightened, and equity markets fell sharply.
The S&P 500 declined approximately 57% from its October 2007 peak to its March 2009 low on a price-index basis.
The crisis showed that risks can spread across companies and industries. Owning many stocks does not eliminate the risk of a broad market decline, particularly when financial conditions deteriorate across the economy.
What investors can learn:
- Diversification reduces some risks but cannot remove all market risk.
- Emergency savings can reduce pressure to sell investments during a downturn.
- Investors should match stock exposure to their time horizon and financial capacity for loss.
- Borrowing to invest can magnify losses and increase the risk of forced selling.
A long-term strategy should anticipate the possibility of substantial losses rather than assume markets will always rise.
Case Study 3: The COVID-19 Market Crash in 2020
In early 2020, the spread of COVID-19 triggered extraordinary uncertainty about public health, business activity, employment, and global supply chains.
U.S. equities fell rapidly in February and March before recovering strongly as conditions and investor expectations changed. The speed of the decline and subsequent recovery made market timing particularly difficult.
Investors who had short-term spending needs tied entirely to stocks faced a different problem from investors investing for retirement decades away.
What investors can learn:
- Diversification does not prevent every short-term loss.
- A portfolio must reflect when money will be needed.
- A predetermined plan can reduce emotional decision-making.
- Predicting the exact bottom or recovery date is extremely difficult.
The lesson is not that investors should ignore risk. It is that portfolio construction, liquidity, and a realistic investment horizon matter before a crisis begins.
Case Study 4: Berkshire Hathaway and Long-Term Business Ownership
Berkshire Hathaway, led for decades by Warren Buffett and also shaped by the contributions of Charlie Munger, illustrates an investment philosophy focused on businesses, capital allocation, and long-term ownership.
The company’s shareholder communications have repeatedly emphasized understanding business economics, evaluating management and financial strength, and avoiding decisions driven solely by short-term market movements.
However, Berkshire Hathaway is a specific company with its own concentrated holdings, insurance operations, and business risks. Its results should not be treated as proof that every investor can reproduce its performance.
What investors can learn:
- Understand what a company does before investing.
- Distinguish business quality from the price paid for its shares.
- Recognize that even respected companies can experience losses.
- Maintain a strategy that reflects your own resources and objectives.
For ordinary investors, diversified index funds may be a simpler alternative to attempting to replicate a successful investor’s individual stock selections.
Example Stock Portfolio Models
The following models demonstrate how allocations can differ. They are educational illustrations, not personalized recommendations.
Conservative Portfolio Example
| Investment category | Allocation |
|---|---|
| Broad stock funds | 30% |
| Bond funds | 50% |
| Cash equivalents | 20% |
| Total | 100% |
This example emphasizes stability and liquidity relative to a stock-heavy portfolio. It still carries inflation risk, bond risk, and potential equity losses.
Balanced Portfolio Example
| Investment category | Allocation |
|---|---|
| Domestic stock funds | 40% |
| International stock funds | 20% |
| Bond funds | 35% |
| Cash equivalents | 5% |
| Total | 100% |
This example combines domestic and international equities with bonds and cash. Its suitability depends on the investor’s time horizon, financial circumstances, and tolerance for losses.
Growth-Oriented Portfolio Example
| Investment category | Allocation |
|---|---|
| Broad domestic stock funds | 50% |
| International stock funds | 30% |
| Small-cap or other diversified equity funds | 15% |
| Cash equivalents | 5% |
| Total | 100% |
This portfolio holds 95% in equities and could experience substantial declines. It may be unsuitable for short-term goals or investors unable to withstand major losses.
The important point is not to copy a model based on age alone. Select an allocation based on the purpose of the money, financial resilience, and investment horizon.
Common Mistakes to Avoid When Building a Stock Portfolio
Chasing Market Hype
Buying a stock because it is trending on social media can lead to decisions based on excitement rather than business fundamentals. Research the company and valuation independently.
Owning Too Few Investments
A portfolio dominated by one or two companies is vulnerable to company-specific events. Broad funds can provide diversification more simply, although their holdings and concentration still need review.
Confusing a High Dividend Yield With Safety
A falling share price can make dividend yield appear unusually high. Investigate cash flow, debt, payout sustainability, and the possibility of a dividend reduction.
Ignoring Fees and Taxes
Transaction charges, fund expenses, foreign-exchange costs, and taxes may reduce net returns. Compare the total cost of investing rather than focusing on one fee.
Panic Selling During Market Declines
Selling during a downturn may turn a temporary decline into a realized loss and can cause investors to miss a subsequent recovery. However, holding indefinitely is not always correct: a changed financial goal or deteriorating investment thesis may justify reassessment.
Treating Past Returns as Future Guarantees
A fund, stock, or strategy that performed well in the past may underperform in the future. Evaluate its purpose, risk, costs, and fit with your plan rather than relying on historical rankings alone.
How to Build a Stock Portfolio: Your Practical Checklist
Before making your first investment, work through these steps:
- Define your investment goal and target date.
- Review debt, emergency savings, and short-term spending needs.
- Establish an appropriate asset allocation.
- Decide whether broad index funds, individual stocks, or a combination fits your knowledge and circumstances.
- Examine diversification across sectors, countries, and underlying holdings.
- Research fund expenses and brokerage charges.
- Understand the tax treatment of your investment account.
- Create a contribution schedule you can sustain.
- Set rules for reviewing and rebalancing the portfolio.
- Record your strategy and the reasons behind important decisions.
A portfolio plan should be clear enough that you can explain why you own each investment and what circumstances would lead you to reconsider it.
Frequently Asked Questions About How to Build a Stock Portfolio
1. How much money do I need to build a stock portfolio?
There is no universal minimum. Some brokerages and funds allow small starting amounts or fractional-share purchases, while others impose minimums. Check transaction costs, fund eligibility, and account requirements before investing.
2. How many stocks should a beginner own?
There is no universally correct number. Holding many individual stocks requires research and does not guarantee diversification. A broad-market fund may provide exposure to numerous companies through a single investment, though the fund’s underlying concentration still matters.
3. Are ETFs better than individual stocks?
Neither is automatically better. Broad ETFs can offer convenient diversification and lower research demands, while individual stocks provide direct exposure to selected businesses but introduce more company-specific risk. The appropriate choice depends on knowledge, time, costs, and objectives.
4. Is a 100% stock portfolio a good idea?
A portfolio entirely invested in stocks can experience severe losses. Whether it is appropriate depends on the investment horizon, ability to tolerate losses, liquidity needs, and other financial resources. A long horizon alone does not make a 100% stock allocation suitable for everyone.
5. How often should I invest in stocks?
Some investors contribute monthly or with each paycheque. Regular contributions can build discipline, but the schedule should reflect income, emergency savings, fees, and the rules of the investment account.
6. How often should I review my stock portfolio?
A scheduled review once or twice a year is a reasonable starting point for many long-term investors, with additional reviews after major changes in financial circumstances. Reviewing does not mean trading frequently.
7. What is the difference between a stock portfolio and an investment portfolio?
A stock portfolio focuses on shares and stock-related investments. An investment portfolio is broader and may also include bonds, cash, property investments, and other assets.
8. Can a diversified stock portfolio lose money?
Yes. Diversification can reduce dependence on individual companies but cannot eliminate broad market risk. Several asset classes and international markets can decline together during periods of economic or financial stress.
9. Should I reinvest dividends?
Reinvesting dividends can increase the number of shares or fund units held and may support compounding. However, investors should consider taxes, transaction costs, cash-flow needs, and whether reinvestment keeps the portfolio aligned with its target allocation.
10. How do I know whether my portfolio is performing well?
Compare performance with an appropriate benchmark and consider total return, fees, taxes, volatility, and the portfolio’s purpose. A portfolio should be evaluated against its own goals and risk level, not simply against the best-performing stock or fund of the year.
Final Thoughts: Build a Portfolio Around a Plan
Learning how to build a stock portfolio begins with a clear objective and continues through asset allocation, diversification, investment research, cost control, and regular review.
Real market history shows why investors should avoid relying on one company, one industry, or predictions about the next market movement. Broad diversification can reduce certain risks, but no portfolio can eliminate losses or guarantee a particular return.
For investors in the United States, United Kingdom, Canada, and Australia, a sound approach also accounts for local taxes, retirement accounts, currency exposure, and financial regulations.
Ultimately, how to build a stock portfolio depends on your personal financial objectives, investment time horizon, risk tolerance, and ability to remain disciplined during market volatility. Review your investments periodically and make changes when your circumstances or financial goals genuinely require them.
The most useful portfolio is not necessarily the most complicated or the one with the highest recent return. It is the portfolio whose risks, costs, and investment strategy align with the investor’s goals and that the investor can maintain through changing market conditions.
Start with a plan, diversify thoughtfully, invest within your financial means, and review your decisions with discipline.