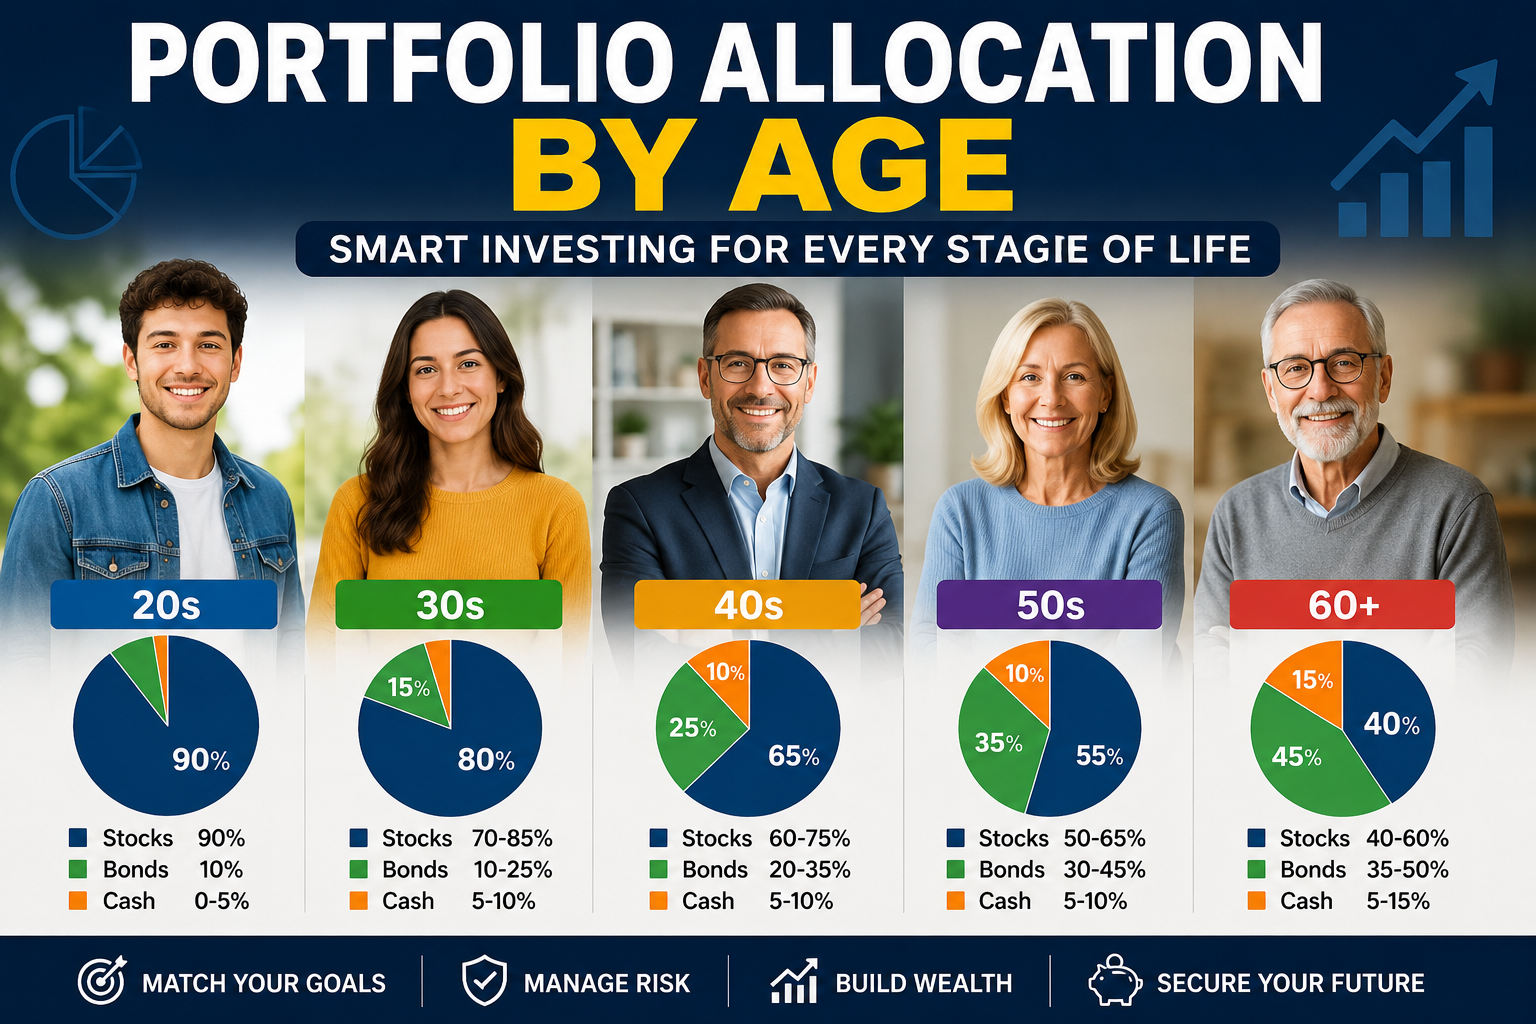
Introduction: Portfolio Allocation by Age
Portfolio allocation by age is a way to plan the mix of stocks, bonds, and cash in an investment portfolio according to an investor’s age, financial goals, time horizon, and ability to tolerate risk. Younger investors saving for distant goals may hold more stocks, while investors approaching retirement may increase their focus on income, liquidity, and managing losses. However, age alone does not determine the right allocation.
However, your age alone cannot determine the ideal investment portfolio. Your financial goals, income stability, existing savings, debt, retirement date, and willingness to tolerate market losses also matter. Two investors who are both 40 years old may need very different portfolios if one plans to retire in five years and the other plans to work for another 25 years.
For investors in the United States, United Kingdom, Canada, and Australia, portfolio allocation by age can help organize retirement investments through accounts such as 401(k)s, IRAs, workplace pensions, ISAs, RRSPs, TFSAs, and superannuation.
In this guide, you will learn how asset allocation works, how investment strategies may change from your 20s to your 70s, what historical market events teach us about risk, and how to create a diversified portfolio that reflects your own circumstances.
Important: The percentages in this article are educational examples, not personalized investment recommendations or guaranteed optimal allocations.
What Is Portfolio Allocation by Age?
Portfolio allocation by age is the process of adjusting the mix of investments as your financial circumstances and time until important goals change.
An investment portfolio is the collection of assets you own. Asset allocation describes how those assets are divided among broad investment categories.
For example, an investor might hold 70% in stocks, 25% in bonds, and 5% in cash. Another investor may hold 40% in stocks, 50% in bonds, and 10% in cash.
The first portfolio has a stronger emphasis on growth. The second places greater emphasis on stability and liquidity, although neither portfolio is guaranteed to avoid losses.
According to Investor.gov’s guide to asset allocation and diversification, an appropriate allocation depends on factors such as risk tolerance and investment time horizon.
Understanding the main investment terms
- Asset allocation: Dividing investments among asset classes such as stocks, bonds, and cash.
- Equities or stocks: Ownership shares in companies. Stocks offer growth potential but can experience substantial price declines.
- Bonds: Debt securities issued by governments or companies. They may provide interest income, but their market prices and credit quality can change.
- Cash equivalents: Short-term, highly liquid instruments designed to provide access to money with relatively low price volatility. They may still face inflation and other risks.
- Liquidity: How easily an asset can be converted into spendable money without a substantial loss in value.
- Capital preservation: An investment objective focused on limiting the risk of losing principal.
- Capital appreciation: An increase in the market value of an investment.
- Portfolio diversification: Spreading investments across different holdings, industries, regions, and asset classes to reduce concentration risk.
Why age is only a starting point
A 28-year-old saving for retirement in 35 years may be able to tolerate short-term market fluctuations. That same person saving for a home deposit needed in 18 months may need a much more conservative strategy for that specific goal.
Similarly, a 65-year-old with a reliable pension and substantial savings may have a greater ability to accept investment risk than another 65-year-old who depends entirely on a small portfolio for living expenses.
The key principle is to match each portfolio to the goal it must fund—not simply to the investor’s birthday.
Why Portfolio Allocation by Age Matters
Portfolio allocation matters because different assets respond differently to economic conditions, interest rates, inflation, and investor sentiment.
Stocks may provide substantial long-term growth but can fall sharply during recessions. High-quality bonds may offer income and diversification, although they can lose value when interest rates rise. Cash provides liquidity but may lose purchasing power if inflation exceeds its return.
An appropriate mix can help you pursue your goals without accepting more risk than you can reasonably afford.
Risk tolerance versus risk capacity
These terms sound similar but mean different things.
Risk tolerance is your emotional willingness to endure investment losses. For example, would you remain invested if your stock portfolio fell 25%?
Risk capacity is your financial ability to withstand those losses. An investor with a stable income, an emergency fund, and decades before retirement may have more capacity to take risk than someone who needs to withdraw money next year.
A suitable portfolio considers both. If you cannot sleep during a market downturn, an aggressive portfolio may encourage panic selling. If you have limited savings and imminent expenses, a risky portfolio may expose you to losses you cannot afford.
Investment horizon and compounding
Your investment horizon is the period between investing your money and needing to use it.
A longer horizon gives investments more time to compound, meaning returns can generate additional returns. However, a long time horizon does not guarantee a profit or guarantee that markets will recover within your required timeframe.
Consider a hypothetical investment of $10,000 earning an assumed 6% annual return, compounded annually, for 20 years. Before fees, taxes, and inflation, it would grow to approximately $32,071. Actual returns would vary, and investments can lose money.
This illustrates why consistent saving and a suitable allocation can work together to build wealth.
Seven Smart Rules for Portfolio Allocation by Age
Rule 1: Start with your financial goals
Before choosing investments, identify what the money is intended to accomplish.
Examples include:
- Retirement in 30 years
- A home purchase in five years
- University expenses in eight years
- Financial independence in 20 years
- Retirement income beginning next year
Each goal may require a separate investment strategy. Money needed soon generally calls for greater attention to liquidity and preservation, while long-term retirement savings may be able to accept more volatility.
Explore The AJ Times’ Start Investing guide for foundational investing concepts.
Rule 2: Understand how much risk you can afford
Do not choose an allocation simply because it appears popular or promises high returns.
Ask yourself:
- How much could my investments fall without jeopardizing essential expenses?
- Do I have emergency savings?
- Will I need to withdraw money during a market downturn?
- How stable is my income?
- Do I have significant debt or financial dependants?
A portfolio should be financially sustainable and emotionally manageable.
Rule 3: Diversify within each asset class
Owning several investments does not automatically mean your portfolio is diversified.
For example, ten technology stocks may all be affected by similar economic or industry risks. A broader portfolio might include domestic and international equities, high-quality bonds, and appropriate cash reserves.
Diversification cannot eliminate market risk, but it can reduce dependence on a single company, industry, or region. The U.S. Securities and Exchange Commission’s asset allocation guide explains the relationship between asset allocation and diversification.
Rule 4: Keep short-term money separate
Money needed for rent, emergencies, tuition, or a near-term house deposit should not automatically be invested in the same way as retirement savings.
A stock-market decline can occur precisely when you need the money. Depending on the goal, an appropriate mix might include insured savings accounts, short-term deposits, or short-duration, high-quality instruments available in your country.
Remember that bonds and bond funds are not identical to cash: they can lose value.
Rule 5: Review and rebalance periodically
Portfolio rebalancing means returning your investments to their intended allocation.
Suppose you begin with 70% stocks and 30% bonds. If stocks perform much better than bonds, stocks might eventually account for 80% of the portfolio. Your overall risk has increased even if you made no new investment decisions.
You could restore your target allocation by directing new contributions toward bonds or, where appropriate, selling some stocks and buying bonds. Consider taxes, transaction costs, and account rules before selling.
Investor.gov explains that investors may rebalance periodically or when allocations move beyond predetermined limits.
Rule 6: Consider fees and taxes
Investment costs reduce the amount of money that remains invested.
The expense ratio is the annual operating expense of a mutual fund or ETF expressed as a percentage of its assets. Other potential costs include trading fees, platform fees, currency conversion costs, and taxes.
Tax treatment depends on your country, account type, and individual circumstances. A US investor may use a 401(k) or IRA, while a UK investor might use a Stocks and Shares ISA or pension. Canadian investors may consider RRSPs and TFSAs, and Australian workers may invest through superannuation.
Do not assume that a tax-advantaged account has identical rules across countries.
Rule 7: Avoid emotional decisions
Fear can lead investors to sell after prices have already fallen. Greed can encourage excessive risk-taking after a strong market rally.
A written investment policy can help. Record your target allocation, investment goals, rebalancing rules, and conditions that would justify a genuine change in strategy.
Review the plan when your circumstances change—not merely because markets have recently risen or fallen.
Portfolio Allocation by Age: Suggested Investment Ranges
Asset allocation models can provide useful starting points, but they are not universal prescriptions. Compare the assumptions behind any model with your own investment horizon, financial goals, and ability to tolerate losses. Vanguard’s model portfolio allocations provide additional context for evaluating different investment mixes.
The following table provides broad educational examples. The percentages are illustrative ranges rather than official industry standards, and each row should be adjusted to the investor’s circumstances.
| Age | Illustrative stocks | Illustrative bonds | Cash and short-term assets |
|---|---|---|---|
| 20–29 | 80–95% | 5–15% | 0–5% |
| 30–39 | 70–85% | 10–25% | 5–10% |
| 40–49 | 60–75% | 20–35% | 5–10% |
| 50–59 | 50–65% | 30–45% | 5–10% |
| 60–69 | 40–60% | 30–50% | 5–15% |
| 70+ | 30–50% | 35–55% | 10–20% |
The percentages in a particular portfolio must total 100%. Because these ranges are independent, choosing the maximum in every column will not necessarily produce a valid allocation.
Also, stocks, bonds, and cash are not the only possible holdings. Real estate investment trusts (REITs), inflation-linked bonds, and other investments may be appropriate in some portfolios, but they introduce their own risks and should not be added merely to make a portfolio appear sophisticated.
Portfolio Allocation by Age in Your 20s: Focus on Long-Term Growth
Investors in their 20s may have decades before retirement. That can provide time to withstand market volatility, especially when they have stable income, manageable debt, and adequate emergency savings.
An illustrative portfolio for a 25-year-old investing for retirement might hold:
| Asset | Allocation |
|---|---|
| Broad domestic stock index fund | 55% |
| International stock index fund | 30% |
| High-quality bond fund | 10% |
| Cash | 5% |
| Total | 100% |
A broad index fund tracks a market index rather than trying to select winning stocks. Combining domestic and international funds can reduce dependence on a single market, although global stock markets can fall together.
Example: A young US investor
Imagine a 25-year-old employee contributing regularly to a workplace 401(k) and, if eligible, a Roth IRA. She chooses diversified index funds and invests a portion of each paycheck.
During a market correction, her stock holdings decline. If her retirement goal remains decades away, her emergency savings are sufficient, and her financial situation has not deteriorated, continuing her planned contributions may be reasonable.
This is an illustrative scenario, not a claim about a documented individual’s investment results. It demonstrates how time horizon, savings discipline, and risk capacity can influence portfolio decisions.
Practical priority: Build emergency savings, manage expensive debt, understand employer retirement contributions, and establish a diversified portfolio before pursuing speculative investments.
Portfolio Allocation by Age in Your 30s: Balance Growth with Responsibilities
In your 30s, income may increase, but financial responsibilities can grow as well. Housing costs, childcare, family support, and education savings may compete with retirement contributions.
A hypothetical 35-year-old could consider an illustrative allocation of 75% stocks, 20% bonds, and 5% cash for long-term retirement savings.
That allocation would not necessarily suit money reserved for a home deposit in three years.
Case example: A Canadian couple
Imagine a couple in Toronto, both aged 35, investing through eligible registered accounts. They hold Canadian and international stock funds alongside high-quality bonds.
They keep their emergency fund separate and save for a future home purchase in a lower-volatility account suited to that shorter goal.
The lesson is that portfolio allocation should reflect the purpose of each account. A retirement portfolio and a home-purchase fund do not need the same asset mix.
Canadian investors should check current eligibility and contribution rules for their RRSPs and TFSAs using official Canadian government resources before making account decisions.
Portfolio Allocation by Age in Your 40s: Strengthen Retirement Readiness
The 40s can be an important period for retirement planning. Investors may have higher incomes, but they may also face mortgages, education expenses, and family responsibilities.
An illustrative allocation could be 65% stocks, 30% bonds, and 5% cash for an investor with a long retirement horizon and moderate-to-high risk capacity.
This is not a rule that every 40-year-old should follow. Someone planning to retire at 50 may need a different strategy from someone expecting to work until 70.
Understand sequence-of-returns risk
Sequence-of-returns risk is the danger that the order in which investment returns occur will affect the sustainability of a portfolio, particularly when withdrawals are being made.
Imagine two retirees who experience the same set of annual returns but in a different order. The investor experiencing severe losses early in retirement while withdrawing money may have fewer assets left to benefit from a later recovery.
That is why investors approaching retirement should consider expected withdrawals, guaranteed income sources, and a suitable reserve for near-term spending.
Explore The AJ Times’ retirement investing guide for related retirement-planning topics.
Portfolio Allocation by Age in Your 50s: Prepare for the Transition
In your 50s, it becomes increasingly important to estimate how much income you may need in retirement and how much of that income could come from pensions or other reliable sources.
An illustrative portfolio might contain 55% stocks, 35% bonds, and 10% cash. A person with a strong pension and a long investment horizon may choose a different mix; someone with limited savings and an early retirement date may need a more careful plan.
What should investors review?
- Expected retirement age and annual spending
- Pension or government-benefit eligibility
- Outstanding mortgage and other debt
- Healthcare and insurance costs
- Portfolio fees and diversification
- Whether retirement savings are on track
Bonds can help diversify a portfolio, but their values fluctuate with interest rates, credit risk, and market conditions. Longer-term bonds are generally more sensitive to interest-rate changes than shorter-term bonds.
Investors should also consider inflation. An allocation that looks safe today may not preserve purchasing power over a retirement lasting several decades.
Portfolio Allocation by Age in Your 60s: Manage Withdrawals and Growth
Retirement does not automatically mean selling every stock investment. Many people need their savings to support 20 or more years of spending, and excessive conservatism may expose them to inflation risk.
An illustrative allocation for a retiree could be 45% stocks, 40% bonds, and 15% cash and short-term assets.
The appropriate mix depends on pension income, withdrawals, health-related costs, dependants, and how much money must remain invested for future years.
Example: An Australian retiree
Consider a hypothetical 67-year-old retiree with superannuation savings and a separate cash reserve for planned expenses. The retiree holds diversified equities for potential long-term growth, high-quality bonds for income and diversification, and cash for near-term spending.
Before changing investments, the retiree reviews withdrawal requirements, fees, tax consequences, and the rules applicable to the specific superannuation account.
The aim is not to eliminate every market fluctuation. It is to create a strategy that can support spending while managing the risks of inflation, market declines, and living longer than expected.
Portfolio Allocation by Age in Your 70s and Beyond
In your 70s and later, the right allocation depends more on spending needs and income sources than on age alone.
A person with a reliable pension and substantial savings may be able to retain a meaningful allocation to stocks. Someone who relies heavily on portfolio withdrawals may need greater liquidity and a more cautious withdrawal strategy.
An illustrative allocation might be 35% stocks, 45% bonds, and 20% cash and short-term assets. This is only an example; maintaining excessive cash for decades can create inflation risk, while holding too little cash can force asset sales during market downturns.
Estate planning, healthcare expenses, support for family members, and the needs of a surviving partner may also influence portfolio decisions.
The “100 Minus Age” Rule: Does It Still Work?
A traditional rule of thumb estimates stock allocation by subtracting the investor’s age from 100.
For example, a 30-year-old would hold 70% stocks, while a 60-year-old would hold 40% stocks under this simplified rule.
Some versions use 110 or 120 instead of 100, producing higher stock allocations. These formulas are easy to remember but do not account for pensions, savings levels, risk capacity, or retirement timing.
They should be treated as rough starting points – not scientifically precise formulas for selecting a portfolio.
A more useful approach is to estimate your investment horizon, identify the losses you could withstand, and select a diversified allocation that supports your financial goals.
Real Historical Case Studies: What Market Crashes Teach Investors
Historical events provide evidence of the risks investors need to plan for. They do not guarantee that future markets will behave in the same way.
Case study 1: The 2007-2009 Global Financial Crisis
The Global Financial Crisis involved severe financial-market disruption. The S&P 500 fell sharply from its 2007 peak to its 2009 trough, with the exact decline depending on the dates and whether prices or total returns are measured. A historical Financial Crisis Inquiry Commission data report documents the scale of the fall.
For historical context, consult the Financial Crisis Inquiry Commission’s economic data report. Historical market declines illustrate why investors should assess their ability to withstand losses rather than assume that a recovery will occur before they need their money.
Lesson for younger investors: A long investment horizon may provide more time to recover from losses, but it does not make losses harmless or guarantee recovery by a specific date.
Lesson for investors approaching retirement: A large decline can be particularly damaging if withdrawals are necessary. Diversification, appropriate cash reserves, and realistic retirement spending assumptions can help manage this risk.
Case study 2: The COVID-19 market shock in 2020
The COVID-19 pandemic triggered an abrupt market sell-off, followed by a substantial recovery in many equity markets. The timing and size of the recovery differed across assets and markets.
Lesson: Even severe short-term volatility does not always predict long-term performance. But investors should not assume every downturn will recover quickly.
Selling in panic can turn a temporary decline into a realized loss. Conversely, staying invested should not be treated as an unconditional rule if a person’s circumstances or financial needs have fundamentally changed.
Case study 3: Target-date retirement funds
Target-date funds are real investment products designed around an approximate retirement year. They generally adjust their allocation over time through a process known as a glide path, usually becoming more conservative as the target date approaches.
The SEC explains that funds can have different glide paths, including approaches that continue changing allocation after the target retirement date.
Before choosing a target-date fund, review its investment strategy, fees, and planned allocation changes. The SEC’s Investor Bulletin on target-date funds explains why funds with the same target retirement year can have different risk profiles.
Lesson: Age-based investing can be automated, but two funds with the same target year may have different strategies, costs, and risk levels. Investors should read the fund’s prospectus and understand its holdings rather than choosing solely by date.
These three examples are documented historical events or product structures, unlike the fictional household scenarios earlier in the article. They demonstrate why a good portfolio strategy requires risk management, diversification, and periodic review.
Stocks vs Bonds vs Cash: How to Choose the Right Mix
Stocks
Stocks represent ownership in businesses. They can deliver capital appreciation and dividends, but share prices fluctuate and individual companies can fail.
Broadly diversified equity funds can help spread company-specific risk. They do not eliminate market-wide losses.
Bonds
Bonds represent lending to a government or company. Depending on their terms, they may provide interest payments and return principal at maturity, assuming the issuer meets its obligations.
Bond prices can fall when market interest rates rise. Corporate bonds also carry credit risk, while inflation can reduce the purchasing power of future payments.
Cash and short-term assets
Cash provides liquidity and can be appropriate for emergencies and near-term expenses. Savings accounts may be protected by deposit-insurance schemes where eligibility requirements are met.
Cash is not a complete long-term growth strategy because its purchasing power may decline during periods of inflation.
International equities and real estate
International stocks expose investors to businesses outside their home country. They can improve geographic diversification but introduce currency and country-specific risks.
Real estate investment trusts (REITs) offer exposure to property-related businesses without requiring the direct purchase of a building. However, REITs can be volatile, and their returns may be affected by interest rates, property markets, and debt levels.
How to Rebalance Your Portfolio
Rebalancing restores the allocation you have chosen for your goals.
Suppose an investor begins with a $100,000 portfolio:
| Asset | Starting value | Starting allocation |
|---|---|---|
| Stocks | $70,000 | 70% |
| Bonds | $25,000 | 25% |
| Cash | $5,000 | 5% |
| Total | $100,000 | 100% |
After market movements, the portfolio grows to $110,000, with stocks worth $85,000, bonds worth $20,000, and cash still worth $5,000.
Stocks now represent approximately 77.3% of the portfolio. If the original 70% target remains appropriate, the investor can consider redirecting new contributions or making trades to restore the intended mix.
The example ignores fees and taxes. In taxable accounts, selling appreciated assets can create tax consequences, so investors should consider their local rules before rebalancing.
Portfolio Allocation by Age in the USA, UK, Canada, and Australia
Retirement accounts and tax rules differ by country. The basic investment principles are similar, but the account-specific details matter.
| Country | Common account or system | What to check |
|---|---|---|
| United States | 401(k), traditional IRA, Roth IRA | Eligibility, contribution limits, employer matching, withdrawal and tax rules |
| United Kingdom | Workplace pension, personal pension, Stocks and Shares ISA | Annual allowances, tax treatment, pension access rules |
| Canada | RRSP, TFSA, workplace pension | Contribution room, tax treatment, withdrawal rules |
| Australia | Superannuation | Contribution limits, preservation rules, retirement-phase treatment |
These accounts do not automatically make an investment suitable. A tax-advantaged account can still contain an overly concentrated or excessively risky portfolio.
For readers in India, the same principles apply, but domestic options, taxation, and retirement arrangements differ. Use locally applicable regulations and account rules rather than copying a US or UK portfolio without adjustment.
Common Portfolio Allocation Mistakes to Avoid
Investing based on age alone
Age is useful, but it cannot replace financial planning. Consider your goal dates, income, savings, debt, and expected withdrawals.
Holding too few investments
A portfolio concentrated in one company, sector, or country can suffer disproportionately when that area performs poorly.
Chasing recent winners
Buying assets simply because they recently rose can lead to excessive exposure and poor timing.
Taking too little risk for a distant goal
An excessively conservative long-term portfolio may not grow enough to meet future spending needs after inflation and fees. This is a risk to assess—not a reason to take more risk than you can tolerate.
Ignoring fees and taxes
Costs compound over time. Review fund expense ratios, account charges, trading costs, and tax treatment.
Forgetting to review the plan
A new child, home purchase, inheritance, career change, or retirement date can alter your financial circumstances. Review your allocation when material changes occur, rather than making frequent adjustments based on market noise.
How to Build Your Own Age-Based Portfolio
Follow this practical sequence before choosing funds or individual securities.
- Define your goal. Identify what the money must fund and when you will need it.
- Review your finances. Account for emergency savings, debt, income stability, and upcoming expenses.
- Assess risk tolerance and capacity. Decide what level of loss is both emotionally manageable and financially survivable.
- Choose an asset mix. Use age-based ranges only as an initial reference.
- Diversify your holdings. Consider domestic and international equities, appropriate bonds, and cash for liquidity.
- Check costs and account rules. Compare fees and understand the tax treatment applicable in your country.
- Set a review schedule. Review at least annually or when a major life event changes your goals. Rebalance when appropriate.
For more related reading, explore Portfolio Strategy, ETFs and Index Funds, Wealth Building, and Personal Finance on The AJ Times. Confirm each URL is live and relevant before publishing.
Frequently Asked Questions About Portfolio Allocation by Age
1. What is the best portfolio allocation by age?
There is no single best allocation for everyone. Younger investors with long horizons may choose more stocks, while people approaching retirement may prefer a more balanced mix. Your financial goals, risk capacity, and expected withdrawals matter as much as age.
2. Should I use the 100 minus age rule?
You can use it as a rough educational starting point, but not as a complete financial plan. It does not account for pensions, income, savings, or the timing of your goals.
3. How much of my portfolio should be in stocks at age 30?
Some illustrative strategies use 70–85% stocks for long-term retirement investing at age 30. The appropriate percentage depends on your risk capacity, time horizon, and financial situation.
4. Should a 60-year-old still invest in stocks?
Possibly. Stocks can help a portfolio pursue growth over a long retirement, but the allocation should reflect spending needs, other income sources, and the ability to tolerate losses.
5. Are bonds safe for retirement?
Bonds can provide income and diversification, but they are not risk-free. Interest-rate changes, inflation, and issuer defaults can affect their value and returns.
6. How often should I rebalance my portfolio?
Many investors review their allocation annually or when it moves beyond a predetermined range. The right schedule depends on your strategy, costs, and tax situation.
7. Are index funds suitable for age-based investing?
Broad index funds can provide diversified exposure at relatively low cost. However, the index, fund fees, market risks, and the overall portfolio mix should be evaluated before investing.
8. Should I hold cash after retirement?
Cash can help cover near-term expenses and reduce the need to sell investments during a downturn. Holding too much cash for a long period, however, may expose retirement savings to inflation risk.
9. What is a target-date fund?
A target-date fund is designed around an approximate future goal date, often retirement. It generally changes its asset mix over time, but different funds may have different glide paths, costs, and investment risks.
10. Can I change my portfolio allocation after a market crash?
You can review your allocation when your circumstances or goals change, but changing it purely out of fear may lock in losses. Reassess your time horizon, risk capacity, and original plan before making decisions.
Conclusion: Build a Portfolio for Your Life, Not Just Your Age
Portfolio allocation by age provides a practical framework for understanding how investment priorities may evolve from early adulthood through retirement. Younger investors often have more time to pursue growth, while investors nearing retirement may need to focus more on withdrawals, liquidity, and managing large losses.
Yet age is only one part of the decision. A well-designed portfolio reflects the goal, investment horizon, risk tolerance, financial capacity, and other income available to the investor. Diversification, careful attention to fees, and periodic rebalancing help maintain that strategy as circumstances change.
Use age-based percentages as a starting point, not a rigid rule. The strongest investment plan is one you understand, can afford to maintain through market volatility, and can adapt when your financial life changes.
Editorial disclaimer: This article is for educational purposes only and does not provide personalized financial, investment, or tax advice. Investments can lose value. Consider consulting a qualified financial professional who understands the regulations and tax rules in your country.