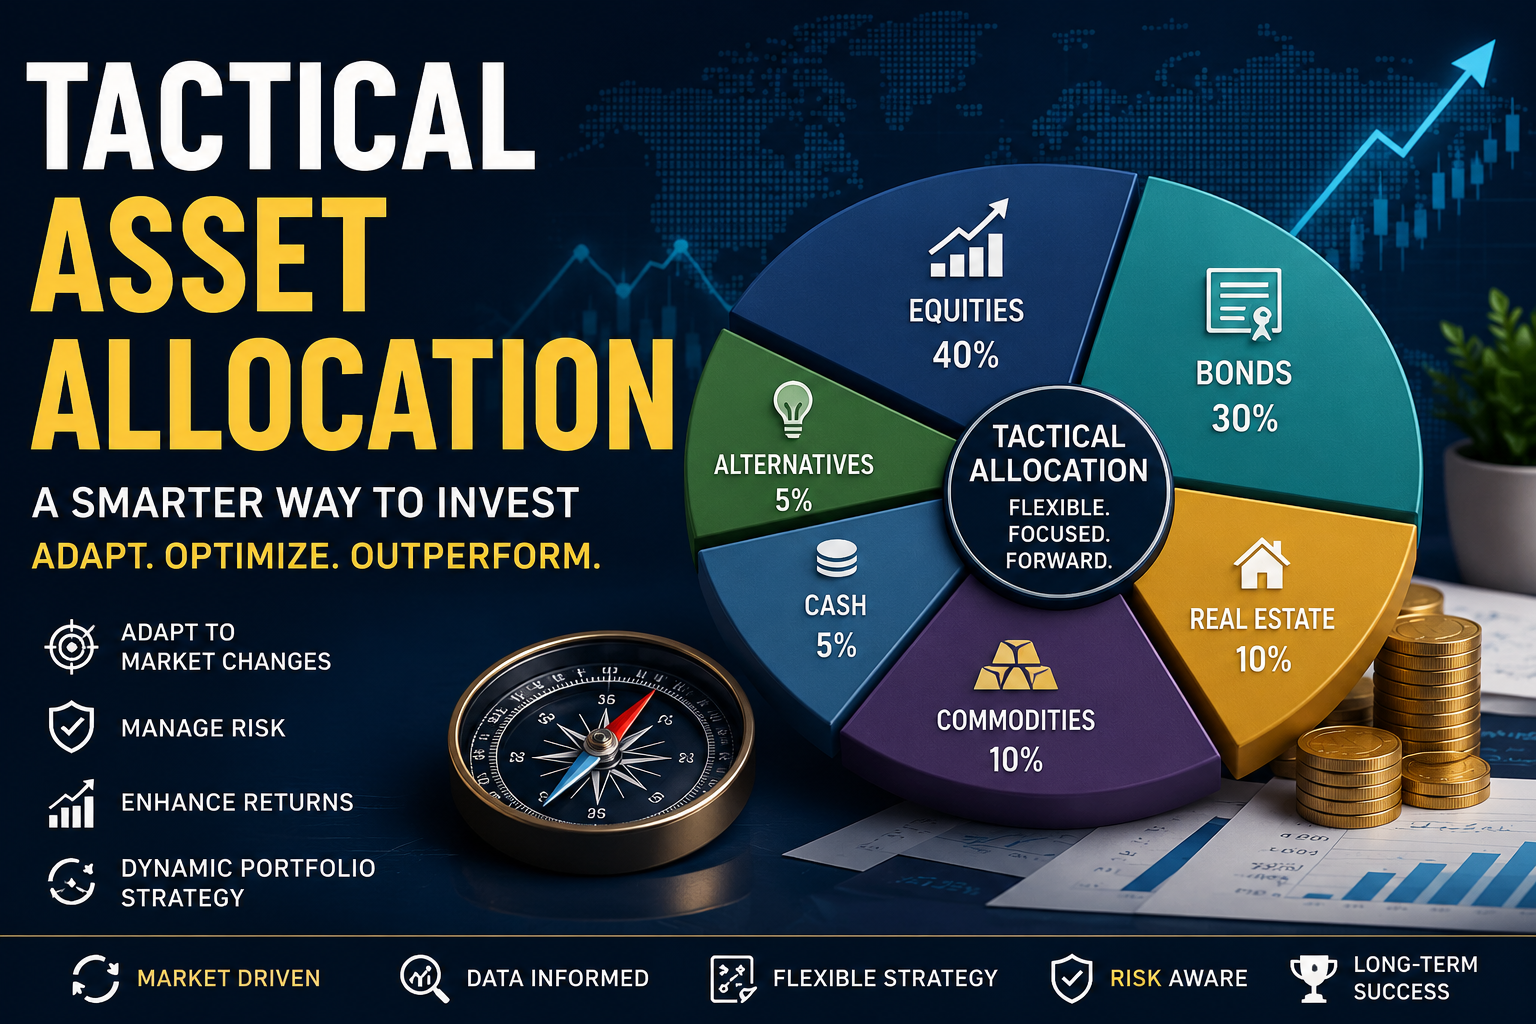
Introduction to Tactical Asset Allocation
Tactical Asset Allocation is an investment strategy that involves temporarily adjusting the percentage of a portfolio invested in different asset classes to respond to changing market conditions, economic developments, valuations, and investment opportunities. Rather than keeping every allocation fixed regardless of circumstances, investors make controlled adjustments around a long-term investment plan.
For example, an investor with a $100,000 portfolio might normally hold 60% stocks, 30% bonds, and 10% cash. If their investment process identifies a compelling opportunity in equities, they might temporarily increase stocks to 65%, reduce bonds to 25%, and maintain 10% cash. This is a hypothetical example, not a recommendation or evidence that the adjustment will improve returns.
Professional investment managers may use economic research, valuation measures, momentum indicators, interest-rate expectations, and quantitative models to guide these decisions. However, predicting market movements consistently is difficult, and tactical decisions can underperform a simple diversified portfolio.
For investors in the United States, United Kingdom, Canada, and Australia, understanding Tactical Asset Allocation can help clarify the relationship between long-term portfolio construction and shorter-term investment decisions, particularly when developing a diversified portfolio strategy.
What Is Tactical Asset Allocation?
Tactical Asset Allocation (TAA) is an active portfolio management approach that deliberately deviates from a strategic asset allocation to pursue potential opportunities or improve the portfolio’s risk-return profile. For a professional perspective on portfolio construction, see the CFA Institute’s overview of asset allocation.
The CFA Institute distinguishes tactical decisions about asset-class weights from decisions about how individual asset classes are implemented. In practice, TAA focuses on whether a portfolio should temporarily hold more or less of a particular asset class than its long-term target.
The strategy may involve adjustments to:
- Equities: Shares of publicly traded companies, including broad-market and sector-specific investments.
- Bonds: Government and corporate debt securities that can provide income but carry interest-rate, inflation, and credit risks.
- Cash and cash equivalents: Highly liquid holdings that can provide flexibility, although inflation can reduce their purchasing power.
- Real estate: Property investments, including publicly traded real estate investment trusts (REITs).
- Commodities: Raw materials such as gold, oil, and agricultural products, whose prices can be volatile.
- International investments: Securities from markets outside the investor’s home country.
- Alternative investments: Other strategies or assets that may have different risk, liquidity, and fee characteristics.
The central objective is not to predict every market movement. It is to make limited, evidence-based allocation changes while preserving the investor’s long-term objectives.
Understanding the Meaning of Tactical Asset Allocation
What Does Tactical Mean?
Tactical refers to a temporary action intended to achieve a specific objective. In investing, a tactical decision responds to an identified opportunity, risk, or market condition.
For example, an investor might temporarily reduce exposure to an asset class after a predefined risk indicator is triggered. The adjustment should follow a documented process rather than an emotional reaction to daily market headlines.
What Is an Asset?
An asset is something with economic or financial value. In portfolio management, an asset class groups investments with broadly similar characteristics, such as equities, bonds, and cash.
Different asset classes react differently to economic growth, inflation, interest rates, and investor sentiment. These relationships can change over time, so diversification does not guarantee protection against losses.
What Does Allocation Mean?
Allocation is the percentage of a portfolio assigned to each investment or asset class.
For example, a $100,000 portfolio with 60% equities has $60,000 invested in equities. If the equity allocation rises to 70%, the equity exposure becomes $70,000, assuming the portfolio remains worth $100,000.
Tactical Asset Allocation changes these percentages temporarily according to a defined investment process.
How Tactical Asset Allocation Works
Step 1: Establish a Strategic Portfolio
An investor first determines a long-term allocation based on financial goals, investment horizon, risk tolerance, liquidity needs, and capacity to absorb losses.
A hypothetical diversified portfolio might target:
| Asset class | Strategic allocation | Value on $100,000 |
|---|---|---|
| Equities | 60% | $60,000 |
| Bonds | 30% | $30,000 |
| Cash | 10% | $10,000 |
| Total | 100% | $100,000 |
This strategic mix is the reference point for subsequent tactical decisions.
Step 2: Evaluate Market Conditions
Investors examine evidence that could affect the relative attractiveness or risk of asset classes. Relevant indicators include inflation, economic growth, employment, corporate earnings, interest rates, bond yields, valuations, and market momentum.
No single indicator reliably predicts future returns. Economic data can also be revised, and markets often respond before official statistics are released.
Step 3: Define a Tactical Adjustment
Suppose an investor’s established process supports a modest increase in equity exposure. The portfolio might temporarily move to 65% equities, 25% bonds, and 10% cash.
The decision should have a clear rationale, a maximum permitted allocation, a review schedule, and conditions for reversing the adjustment.
Step 4: Monitor Performance and Risk
The investor tracks the tactical position against its benchmark, the strategic portfolio, and relevant risk limits. Performance should be assessed after trading costs and taxes where applicable.
Step 5: Return Toward the Strategic Target
When the original investment thesis no longer holds, or a predefined review rule is triggered, the investor reduces or reverses the tactical position. This prevents a temporary decision from silently becoming a permanent change in risk.
Tactical Asset Allocation vs. Strategic Asset Allocation
Strategic Asset Allocation sets the portfolio’s long-term asset mix. Tactical Asset Allocation temporarily deviates from that mix to pursue an opportunity or manage a specific risk.
| Feature | Strategic allocation | Tactical allocation |
|---|---|---|
| Primary purpose | Meet long-term financial goals | Pursue opportunities or adjust risk |
| Time horizon | Generally long term | Usually short to medium term |
| Decision process | Goals, risk tolerance, expected returns | Market evidence and short-term expectations |
| Portfolio changes | Periodic rebalancing | Deliberate temporary deviations |
| Trading activity | Often relatively low | Can be higher |
| Main challenge | Selecting a suitable long-term mix | Making accurate, disciplined adjustments |
These approaches are not mutually exclusive. An investor can maintain a strategic core while allowing a limited tactical range around it. Investors can learn more about the role of diversification and portfolio weights in the SEC’s investor education guide to asset allocation and diversification.
10 Tactical Asset Allocation Strategies
1. Momentum-Based Allocation
Momentum investing gives greater weight to assets that have recently demonstrated relative strength. The underlying idea is that some market trends may persist, although they can reverse abruptly.
A quantitative investor might compare the recent performance of diversified equity, bond, and commodity funds against their own historical trends. A predefined model could reduce exposure to assets with weakening momentum.
Key risk: Momentum can reverse suddenly, leading to losses when an investor enters late or exits after a short-lived decline.
2. Valuation-Based Allocation
Valuation-based allocation compares asset prices with measures such as earnings, cash flows, book value, or historical valuation ranges.
For example, an investor might find that one equity market has a relatively high valuation compared with another. That finding could support a modest relative allocation adjustment, but valuation alone does not tell the investor when prices will change.
Key risk: An asset that appears expensive can continue rising, while an apparently cheap asset can remain depressed for years.
3. Economic-Cycle Allocation
Economic-cycle strategies consider how assets may respond during periods of expansion, slowing growth, recession, and recovery.
Equities may benefit from improving earnings expectations, while high-quality government bonds may provide diversification during some growth shocks. Commodities and cyclical sectors can respond differently depending on supply constraints and inflation.
However, there is no universal asset allocation that reliably wins in every economic phase. Markets frequently anticipate economic changes before they appear in published data.
4. Interest-Rate-Based Allocation
Interest rates influence borrowing costs, bond prices, corporate valuations, and currency markets.
When market interest rates rise, existing fixed-rate bonds generally fall in price, with longer-duration bonds usually more sensitive to the change. Higher discount rates can also pressure equity valuations, particularly for companies whose expected cash flows lie far in the future.
A tactical investor might adjust bond duration or the balance between cash and bonds based on a documented interest-rate outlook.
Key risk: Markets often price in expected central-bank decisions before they occur, so correctly predicting a rate change does not automatically produce a profitable trade.
5. Inflation-Sensitive Allocation
Inflation reduces the purchasing power of money and can affect corporate profit margins, bond returns, and consumer spending.
Depending on the source and persistence of inflation, investors may assess inflation-linked government bonds, commodities, selected equities, and other assets with different sensitivities to price changes.
For example, US Treasury Inflation-Protected Securities (TIPS) adjust their principal according to a specified inflation index. Their market prices can nevertheless fall when real yields rise.
Key risk: An asset associated with inflation protection may perform poorly if purchased at an unattractive price or if other market forces dominate.
6. Sector-Rotation Allocation
Sector rotation changes exposure to groups of companies, such as technology, healthcare, financials, industrials, utilities, and consumer staples.
A manager anticipating stronger capital spending might investigate industrial companies. During slowing consumer demand, the manager might assess whether more defensive businesses deserve a relatively larger allocation.
These are hypotheses to test, not dependable rules. Defensive sectors can decline, and cyclical sectors can outperform even during weak economic conditions.
7. Global and Regional Allocation
Global allocation adjusts exposure across markets such as the United States, United Kingdom, Canada, Australia, Europe, and emerging economies.
Investors may evaluate relative valuations, economic growth, currency exposure, interest rates, and geopolitical risks.
For instance, a Canadian investor whose income, property, and employment are already tied to Canada may consider whether their investment portfolio is excessively concentrated in domestic financial and energy companies.
International diversification can broaden opportunities, but it introduces currency, political, regulatory, and market-specific risks.
8. Quantitative and Rules-Based Allocation
Quantitative strategies use measurable inputs and predefined rules instead of relying entirely on subjective forecasts.
A model might evaluate momentum, volatility, valuation, or the relationship between assets. It then applies rules to determine whether allocations should change.
A robust model requires careful testing, realistic trading-cost assumptions, and independent validation. Historical success does not guarantee future results.
Key risk: Overfitting occurs when a model is tailored too closely to historical data and fails to perform under new market conditions.
9. Volatility-Targeting Allocation
Volatility-targeting strategies adjust portfolio exposure in response to estimated fluctuations in asset prices.
For example, a model may reduce exposure when measured portfolio volatility rises above a predefined threshold. The objective is to control risk, not necessarily to forecast market direction.
This approach can be useful during periods of changing volatility, but it can also reduce exposure after prices have already fallen and increase exposure after markets have recovered.
10. Core-Satellite Allocation
A core-satellite portfolio combines a diversified strategic core with a smaller allocation to active or tactical positions.
For example, an illustrative $100,000 portfolio might place $80,000 in a diversified long-term portfolio and reserve $20,000 for carefully limited tactical strategies.
The core is designed around long-term objectives; the satellite allocation provides room to express specific views without allowing the entire portfolio to depend on market timing.
The satellite portion should still have explicit limits, cost controls, and a clear benchmark.
Real Market Case Studies: What History Teaches Investors
Historical events help explain why tactical decisions can be tempting. They do not prove that investors could have anticipated events in advance or consistently profited from them.
Case Study 1: The Global Financial Crisis of 2008
The global financial crisis involved severe stress in financial institutions, housing markets, credit markets, and the wider economy. Equity markets suffered substantial losses, while the performance of bonds differed according to credit quality, duration, and the timing of transactions.
A tactical manager concerned about deteriorating credit conditions might have reduced exposure to financial equities, reviewed corporate bond risk, or increased the allocation to liquid, high-quality government securities.
However, the decision would have required timely information and an exit rule. An investor who reduced equities after a large decline could have locked in losses or missed a subsequent recovery.
Lesson: Risk controls and diversification can matter greatly during a crisis, but identifying the exact market peak or bottom is not a realistic assumption for a repeatable strategy.
Case Study 2: The COVID-19 Market Shock in 2020
The COVID-19 outbreak triggered extraordinary uncertainty in March 2020. Equity prices fell sharply, Treasury yields reached historically low levels, and credit markets experienced significant stress. Central banks and governments subsequently introduced substantial policy responses.
The Federal Reserve’s 2020 monetary policy report provides additional context on monetary policy and economic conditions during that period. Historical market data can also be explored through the Federal Reserve Bank of St. Louis’ analysis of US economic and financial market conditions during the COVID-19 outbreak.
These events created several competing tactical signals. Falling yields could support existing government bond prices, while collapsing economic activity and market stress could damage equities, corporate credit, and commodities.
An investor using a rules-based approach might have monitored liquidity, volatility, credit spreads, and asset-class momentum before adjusting risk. Another investor might have maintained a strategic allocation and rebalanced after equities fell.
Both approaches could produce different results depending on timing, costs, and the eventual market recovery.
Lesson: Rapid policy responses and sharp reversals make crisis trading difficult. A tactical strategy should not assume that cash, bonds, or equities will always behave in a predictable way.
Case Study 3: Inflation and Rising Interest Rates in 2022
In 2022, major central banks tightened monetary policy as inflation remained elevated. Higher yields put pressure on many existing bonds and on equity valuations, illustrating that bonds do not always offset stock-market losses during inflationary shocks.
A hypothetical tactical manager might have reviewed exposure to long-duration bonds, inflation-linked securities, cash, and companies sensitive to borrowing costs.
The appropriate decision would have depended on starting valuations, expected inflation, real yields, portfolio objectives, and the investor’s ability to withstand losses.
Lesson: Diversification should be based on how assets respond to different economic risks, not on the assumption that two different asset classes must always move in opposite directions.
These three cases are documented historical market events. The portfolio responses described above are illustrative decisions, not claims that a specific manager achieved a particular return through tactical allocation.
A Worked Tactical Asset Allocation Example
Consider an illustrative investor with a $100,000 portfolio and a long-term target of 60% equities, 30% bonds, and 10% cash.
After reviewing a predefined set of indicators, the investor decides to make a limited tactical change to 55% equities, 35% bonds, and 10% cash.
| Asset class | Before | After |
|---|---|---|
| Equities | $60,000 | $55,000 |
| Bonds | $30,000 | $35,000 |
| Cash | $10,000 | $10,000 |
| Total | $100,000 | $100,000 |
The investor shifts $5,000 from equities to bonds. This is a five-percentage-point reduction in equity allocation, not a forecast that equities will necessarily fall.
If equities subsequently outperform bonds, the tactical change may underperform the original portfolio. If bonds outperform equities over the measurement period, it may help. Trading costs, taxes, interest income, and the performance of the underlying securities also matter.
To evaluate the decision fairly, the investor should compare the actual portfolio with the original strategic portfolio over the same period and account for costs and risk.
Measuring Tactical Asset Allocation Performance
Return
Return measures the gain or loss on an investment over a specified period, including relevant income and distributions.
A higher return alone does not prove that a tactical strategy is superior because the strategy may have taken more risk.
Volatility and Standard Deviation
Volatility describes how much investment returns fluctuate. Standard deviation is a common statistical measure of that variation.
A strategy with lower volatility may provide a smoother experience, but it can still suffer a large loss.
Maximum Drawdown
Maximum drawdown measures the largest peak-to-trough decline in portfolio value during a specified period before a new peak is reached.
It helps investors understand the severity of historical losses, although future drawdowns can be larger.
Sharpe Ratio
The Sharpe ratio compares a portfolio’s excess return over a chosen risk-free rate with the volatility of its returns. A higher value can indicate better historical risk-adjusted performance, but comparisons require consistent measurement periods and assumptions.
Tracking Error
Tracking error measures how much a portfolio’s returns vary relative to a benchmark. It is useful when assessing how differently a tactical portfolio behaves from its strategic reference portfolio.
A sensible evaluation should include returns after costs, drawdowns, volatility, taxes where relevant, and performance against an appropriate benchmark.
Tactical Asset Allocation: Advantages and Disadvantages
Advantages
Flexibility: Investors can respond to changing economic conditions rather than relying exclusively on fixed weights.
Risk management: Defined allocation limits may help control unwanted exposures.
Opportunity seeking: Tactical changes can pursue relative-value, momentum, or other market opportunities.
Portfolio customization: Investors can adjust exposures to reflect particular risks or investment objectives.
Disadvantages
Forecasting uncertainty: Markets can move differently from expectations, even when economic analysis is sound.
Higher costs: Frequent trading can increase transaction costs, fund expenses, and taxable events.
Behavioral mistakes: Fear, greed, and overconfidence can undermine a disciplined strategy.
Model risk: Quantitative strategies may fail when market relationships change.
Opportunity cost: Reducing exposure before a recovery can cause an investor to miss significant gains.
Tactical Asset Allocation is therefore not automatically better than strategic investing. Its value depends on whether the decision process adds enough benefit to compensate for its costs and risks.
How to Implement Tactical Asset Allocation Responsibly
Establish Clear Limits
Define the strategic allocation, the maximum permitted deviation, the investment thesis, and the conditions for reversing a position before trading.
Diversify Within Asset Classes
Holding several funds does not necessarily create diversification if they own the same securities or respond to the same risks. Review their underlying holdings and exposures.
Use Appropriate Benchmarks
Compare the tactical portfolio with a suitable strategic portfolio, not just with whichever market index performed best.
Review Taxes and Fees
Tax rules differ across countries and account types. Fund expenses and transaction costs can also reduce an investor’s net returns over time, making it important to understand how expense ratios impact long-term investment returns. US investors may need to consider short-term capital gains; UK investors may consider ISA eligibility; Canadian investors should review account-specific tax treatment; and Australian investors should understand capital gains and superannuation rules. Obtain country-specific tax advice when needed.
Keep Records
Record the reason for every tactical decision, the evidence available at the time, the expected holding period, and the rule for exit. This makes it easier to distinguish a repeatable process from hindsight.
Tactical Asset Allocation for US, UK, Canadian, and Australian Investors
Investors in different countries face different market structures, tax rules, currencies, and retirement systems.
United States: Investors may monitor Federal Reserve policy, Treasury yields, inflation data, corporate earnings, and the implications of asset placement in taxable and tax-advantaged accounts.
United Kingdom: Investors may consider Bank of England policy, sterling exposure, global equity concentration, and the tax treatment of investments held inside or outside an ISA.
Canada: Investors may evaluate exposure to domestic banks, energy companies, the Canadian dollar, and US or international markets. Registered accounts have their own tax and withdrawal rules.
Australia: Investors may examine Reserve Bank of Australia policy, mining and financial-sector concentration, currency movements, and the structure of superannuation investments.
Investors planning for retirement should also consider how asset allocation, investment costs, withdrawal needs, and risk tolerance change as their financial goals approach.
These are examples of factors to evaluate, not country-specific investment recommendations. The appropriate allocation still depends on each investor’s goals, time horizon, financial circumstances, and risk capacity.
Frequently Asked Questions About Tactical Asset Allocation
1. What is Tactical Asset Allocation in simple terms?
Tactical Asset Allocation means temporarily changing the percentages invested in stocks, bonds, cash, or other asset classes to respond to perceived market opportunities or risks while maintaining a long-term investment framework.
2. Is Tactical Asset Allocation better than Strategic Asset Allocation?
Not necessarily. Tactical allocation may add value when decisions are timely and cost-effective, but poor forecasts and trading costs can cause it to underperform a strategic portfolio. The better approach depends on the investor and the evidence supporting the strategy.
3. How often should investors change tactical allocations?
There is no universally correct frequency. Some strategies review signals monthly or quarterly, while others react to predefined risk thresholds. The review schedule should fit the strategy, transaction costs, and quality of the available data.
4. Can beginners use Tactical Asset Allocation?
Beginners can learn the principles, but frequent allocation changes can be difficult to manage. Understanding diversification, risk tolerance, fees, and strategic rebalancing is a sensible starting point for beginners who want to start investing before attempting active market timing.
5. Which asset classes can be used in Tactical Asset Allocation?
Common choices include equities, government and corporate bonds, cash equivalents, real estate securities, commodities, and international investments. Each has different liquidity, volatility, valuation, and risk characteristics.
6. Does Tactical Asset Allocation protect investors during market crashes?
It may reduce exposure to some risks if the decisions are timely, but it cannot guarantee protection. Rapid declines, market gaps, and reversals can make exits difficult, and defensive assets can also lose value.
7. What is the difference between tactical allocation and portfolio rebalancing?
Rebalancing restores a portfolio to its target allocation after market movements cause weights to drift. Tactical allocation deliberately moves away from the strategic target to pursue an investment view. Rebalancing does not necessarily require a market forecast.
8. Do ETFs work for Tactical Asset Allocation?
ETFs and index funds can provide convenient access to broad markets, bonds, sectors, and commodities, depending on the fund’s investment objective and underlying holdings. Investors should examine expense ratios, spreads, liquidity, tracking differences, concentration, and tax treatment before selecting a fund.
9. What is a reasonable tactical allocation limit?
There is no single suitable limit for everyone. A limit should reflect risk capacity, the strategic portfolio, investment horizon, and the strategy’s historical and expected behavior. The key is to set the limit before market stress occurs.
10. Can Tactical Asset Allocation generate consistent excess returns?
It can seek excess returns, but consistent outperformance is difficult to achieve. Investors should assess performance over multiple market environments, account for costs and taxes, and avoid relying solely on selected historical examples.
Final Thoughts on Tactical Asset Allocation
Tactical Asset Allocation provides a framework for making temporary, evidence-based changes to a long-term portfolio. By considering valuations, momentum, economic conditions, interest rates, and risk measures, investors can develop a structured approach to allocation decisions.
Historical events such as the 2008 financial crisis, the 2020 pandemic shock, and the 2022 inflation and interest-rate environment demonstrate that market relationships change. They also show why forecasts can be wrong and why a defensive allocation does not guarantee positive returns.
For many long-term investors, the practical starting point is a diversified strategic portfolio, a clear rebalancing policy, low investment costs, and a carefully limited tactical component only when there is a documented reason to use one.
The goal is not to predict every market move. It is to make decisions consistently, measure their results honestly, and keep the portfolio aligned with the financial goals it is meant to serve as part of a disciplined, long-term wealth-building plan.
Financial disclaimer: This article is for educational purposes only and does not provide personalized financial, investment, or tax advice. All investments involve risk, including possible loss of principal. Historical performance does not guarantee future results. Consider consulting a qualified financial or tax professional before making investment decisions.