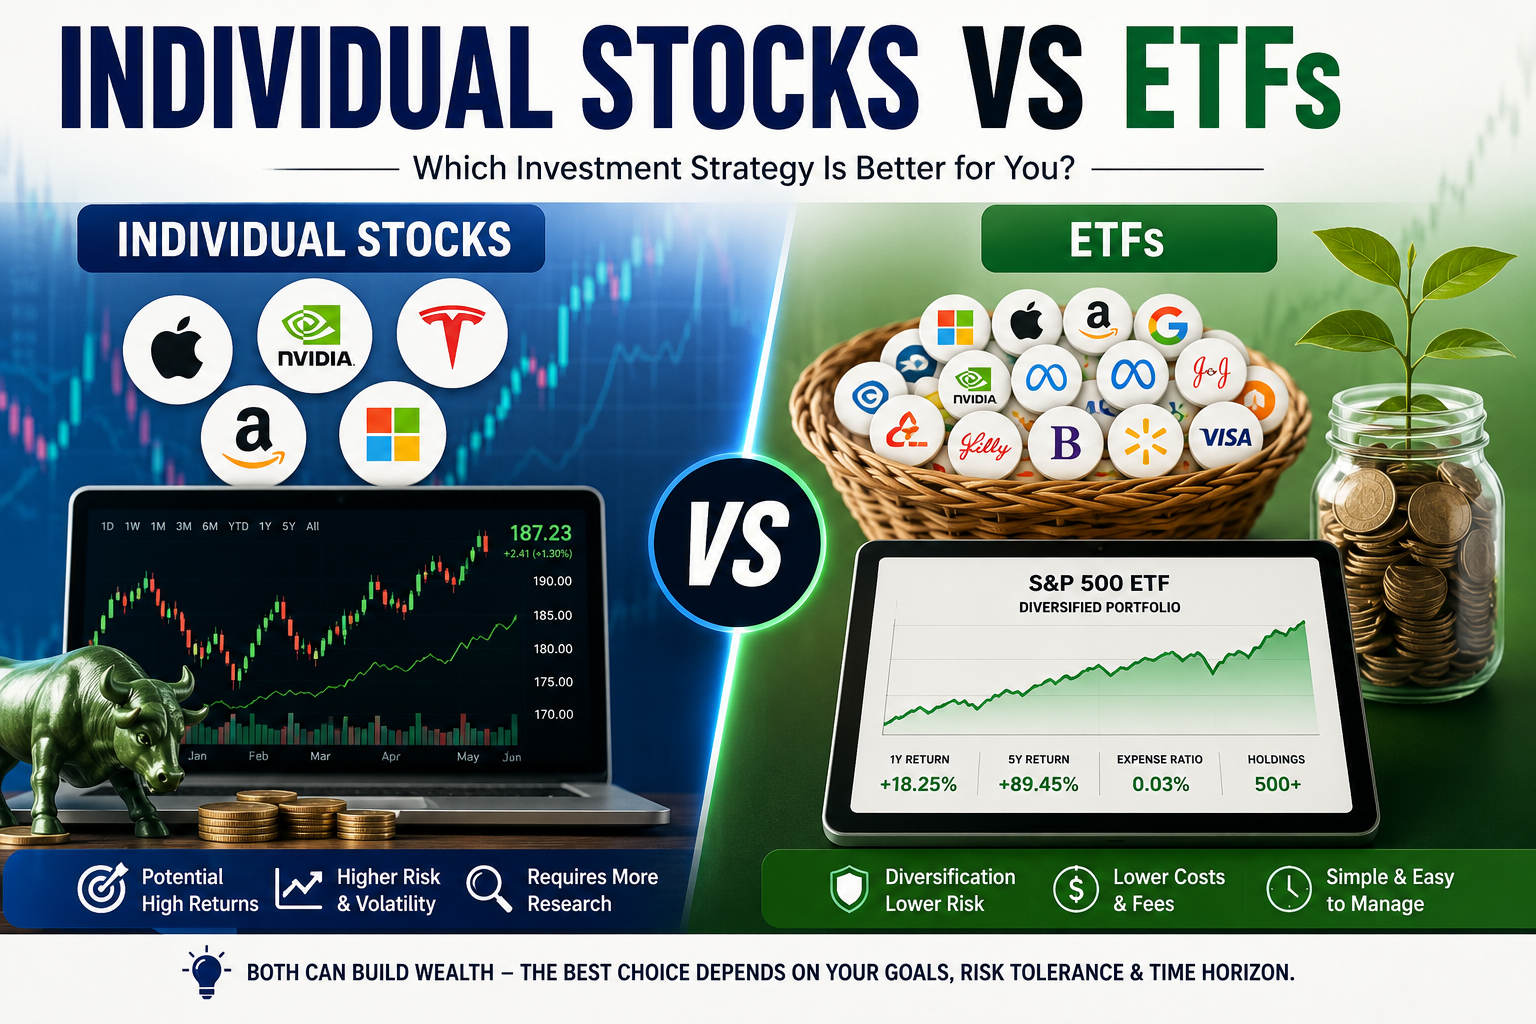
Should You Buy Individual Stocks or Stick to ETFs?
Investing in individual stocks vs ETFs is an important decision for anyone who wants to build long-term wealth. Individual stocks offer the opportunity to benefit from the growth of a specific business, while exchange-traded funds (ETFs) allow investors to own a collection of investments through a single fund. Each approach has different risks, costs, research requirements and potential outcomes.
Consider two investors. The first researches individual companies, studies financial statements and purchases shares of businesses they believe will grow. The second invests regularly in diversified ETFs that track broad stock market indexes. Both investors want to grow their money, but they follow different strategies.
Which approach is better? The answer depends on your financial goals, investment knowledge, time horizon, risk tolerance and ability to remain disciplined during market downturns. If you are new to investing, start with our guide on how to start investing to understand the fundamentals before choosing individual stocks or ETFs.
This guide to individual stocks vs ETFs explains the differences, examines real-world business case studies, compares investment costs, explores portfolio strategies and answers common questions. It is designed to help beginners and experienced investors understand their choices without assuming that one investment method guarantees better results.
What Are Individual Stocks?
An individual stock is a security representing an ownership interest in a company. When you purchase a share of a publicly traded business, you become a shareholder and gain exposure to that company’s financial performance.
For example, purchasing shares of Apple gives you an ownership interest in Apple. If the company grows its earnings and investors become willing to pay more for its shares, your investment may increase in value. If the business struggles or its valuation falls, your investment can lose value.
How Individual Stock Investing Works
Suppose you invest $1,000 in a company at $100 per share. Ignoring trading costs and taxes, you purchase 10 shares.
If the share price increases to $130, your investment becomes worth $1,300, producing a $300 gain, or 30%.
However, if the share price falls to $60, your investment becomes worth $600, creating a $400 loss, or 40%.
These are hypothetical calculations, not predictions of any particular company’s future performance.
Individual stock investors may earn returns through two primary sources:
- Capital appreciation: An increase in the market price of shares.
- Dividends: Payments a company distributes to eligible shareholders from its earnings or other available funds.
Dividends are not guaranteed, and companies can reduce or suspend them. Similarly, a profitable business does not automatically have an attractive stock price because investors may already have priced its expected growth into the shares. For a broader introduction to stock market investing, learn how shares are traded and how stock prices can change.
What Makes Individual Stocks Attractive?
Individual stocks appeal to investors who want to research businesses and identify opportunities that the broader market may undervalue.
An investor might examine a company’s revenue growth, profitability, competitive advantages, debt, cash flow, management quality and valuation before deciding whether to purchase its shares.
This approach is called stock picking. It requires investors to make judgments about both the quality of a business and the price they are paying for it.
The potential reward is substantial if an investor identifies a successful business early and holds it through years of growth. The challenge is that identifying future winners consistently is difficult, even for experienced professionals.
What Is an ETF?
An exchange-traded fund, commonly called an ETF, is an investment fund whose shares trade on a stock exchange. Depending on its investment strategy, an ETF may hold stocks, bonds, commodities or other assets.
Rather than purchasing shares in one company, investors can buy ETF shares representing an interest in a portfolio of underlying investments.
For example, an ETF tracking the S&P 500 seeks to follow an index representing approximately 500 leading publicly traded US companies. Buying such an ETF provides exposure to many companies through a single investment.
However, an ETF does not automatically eliminate investment risk. Its performance depends on the assets it holds, its investment strategy, expenses and market conditions.
How ETF Investing Works
Imagine investing $1,000 in a diversified ETF that holds hundreds of companies.
If some companies perform poorly while others perform well, the results of the stronger holdings may offset some of the weaker holdings. Your investment is not dependent on a single business in the same way that a one-stock portfolio is.
This is called diversification, which means spreading investments across multiple securities or asset classes to reduce dependence on any one investment.
Diversification cannot prevent all losses. If the overall stock market falls, a stock-market ETF can also decline substantially. Explore our guide to ETF and index fund investing to learn more about fund types, index tracking and diversification.
Common Types of ETFs
1. Broad-market index ETFs: These track indexes covering large sections of a stock market. Examples include the Vanguard S&P 500 ETF (VOO) and iShares Core S&P 500 ETF (IVV).
2. Total-market ETFs: These aim to provide exposure to a broad range of companies across different market capitalizations.
3. Sector ETFs: These concentrate on particular industries, such as technology, healthcare, energy or financial services.
4. Dividend ETFs: These invest according to dividend-related criteria, such as dividend yield, dividend growth or dividend quality.
5. Bond ETFs: These hold portfolios of bonds, which may include government or corporate debt.
6. International ETFs: These provide exposure to companies or markets outside an investor’s home country.
An important distinction is that not all ETFs are broadly diversified. A technology ETF or a narrowly focused thematic ETF may expose investors to considerable sector-specific risk.
Individual Stocks vs ETFs: Key Differences
The principal difference is the number and type of investments you own. An individual stock provides exposure to one company, whereas an ETF provides exposure to a portfolio determined by its investment mandate.
| Feature | Individual stocks | ETFs |
|---|---|---|
| Ownership | Interest in one company per stock | Interest in a fund holding underlying investments |
| Diversification | Requires multiple holdings | Can provide diversification through one fund |
| Research | Company-specific financial analysis | Fund strategy, holdings, fees and risk analysis |
| Potential performance | Can substantially outperform or underperform the market | Depends on the fund and its underlying holdings |
| Company-specific risk | Can be high | Usually reduced in broadly diversified funds |
| Costs | Trading costs and possible taxes | Expense ratio, trading costs and possible taxes |
| Time commitment | Often greater for active stock selection | Often lower for a simple, long-term strategy |
| Income | Dividends, when declared | Distributions from the fund, depending on holdings |
| Best use | Selective exposure to individual businesses | Building diversified market exposure |
Neither approach is universally superior. A concentrated portfolio of individual stocks can outperform a broad ETF, but it can also suffer losses that a diversified portfolio might have avoided.
Advantages of Buying Individual Stocks
1. Greater Potential to Outperform the Market
A successful individual stock can generate returns far above those of a broad market index. An investor who correctly identifies a rapidly growing business may benefit from increasing profits, expanding markets and improving competitive advantages.
However, the possibility of exceptional returns should not be confused with a high probability of achieving them. Future business success is uncertain, and a strong company can still be a poor investment if its shares are purchased at an excessive valuation.
2. Direct Control Over Investment Choices
Stock investors can decide exactly which companies to own. They may prefer businesses with strong balance sheets, sustainable competitive advantages, growing cash flow or particular ethical standards.
This flexibility can be useful for knowledgeable investors who understand the risks associated with their decisions.
3. Opportunities to Generate Dividend Income
Some established companies distribute a portion of their earnings to shareholders. Investors who select dividend-paying stocks may receive periodic income while retaining ownership of their shares.
However, a high dividend yield can sometimes signal financial difficulties. Investors should evaluate the sustainability of dividends rather than selecting stocks solely because their yields look attractive.
4. Greater Customization
Investors can exclude companies, limit exposure to particular industries or emphasize businesses they understand well. This customization is more direct than relying on a fund’s predetermined holdings.
Disadvantages of Buying Individual Stocks
1. Company-Specific Risk
A company’s stock can fall because of weak management, declining sales, technological disruption, regulatory problems, excessive debt or accounting irregularities.
When most of your money is invested in a few companies, a single business failure can seriously damage your portfolio.
2. Significant Research Requirements
Responsible stock selection involves examining financial statements, earnings reports, valuation metrics, industry conditions and management decisions. Investors must also monitor whether the original investment thesis remains valid.
This work can be difficult for people with limited financial knowledge or little time to research businesses.
3. Emotional Decision-Making
Investors may buy shares during periods of excitement and sell them when fear dominates the market. They may also become emotionally attached to a company and ignore deteriorating fundamentals.
Such behaviour can turn a reasonable investment strategy into an expensive cycle of buying high and selling low.
Advantages of Investing in ETFs
1. Diversification Through a Single Investment
A broad-market ETF can provide exposure to hundreds or thousands of underlying securities, depending on the index or portfolio it tracks.
This reduces dependence on the performance of one company. The US Securities and Exchange Commission’s investor education resource explains how mutual funds and ETFs can make diversification easier, while warning that narrowly focused funds may not provide sufficient diversification. See Investor.gov’s guide to asset allocation and diversification.
2. Lower Research and Maintenance Requirements
A passive index ETF follows an established index methodology rather than requiring the investor to select every company individually.
Investors still need to understand the fund’s holdings, expenses, risks and suitability. However, a simple diversified ETF strategy generally requires less company-by-company research than active stock picking.
3. Competitive Costs
Many broad-market index ETFs have relatively low expense ratios. The expense ratio is the annual operating expense charged by a fund, expressed as a percentage of its assets.
For example, a fund with a 0.10% expense ratio would have an approximate annual expense of $10 on a constant $10,000 investment, before considering changes in asset value and other costs.
Investors should also consider brokerage commissions, bid-ask spreads, taxes and currency conversion charges where applicable. See how expense ratios affect investment returns over 20 years and why small annual fees can matter over time.
4. Easier Long-Term Portfolio Management
Investors can use ETFs to build a portfolio aligned with their goals without regularly evaluating dozens of individual businesses.
A simple portfolio may combine broad equity ETFs with bond funds or cash, depending on the investor’s time horizon and ability to tolerate losses.
Disadvantages of ETF Investing
ETFs are convenient, but they have limitations.
Market risk: A broad equity ETF can lose substantial value during a stock market downturn.
Limited control: Investors generally cannot choose individual companies within an index ETF without selecting a different fund or purchasing stocks separately.
Concentration within the fund: Market-capitalization-weighted indexes may allocate a large portion of their assets to the biggest companies. Owning hundreds of stocks does not necessarily mean having equal exposure to every company or industry.
Fees and tracking differences: An ETF’s performance may differ from its benchmark because of expenses, trading costs, portfolio construction and other factors.
Strategy risk: Leveraged, inverse, thematic and narrowly focused ETFs may be substantially more complicated or risky than a broad-market index fund.
Therefore, choosing an ETF requires understanding what it actually owns rather than assuming that every fund is automatically diversified or safe.
Real Case Study 1: NVIDIA and the Opportunity in Individual Stocks
NVIDIA provides an example of how an individual company can experience extraordinary growth when its products benefit from a major technological shift.
The company developed a strong position in graphics processing units, initially associated with computer graphics and gaming. Over time, its technology also became important in accelerated computing and artificial intelligence infrastructure.
As demand for AI computing expanded, investors reassessed the company’s growth prospects, contributing to substantial movements in its share price.
For an investor who purchased NVIDIA before much of this growth was reflected in its valuation and held through the subsequent expansion, the results could have been exceptional.
However, this is a retrospective example. The outcome was not obvious in advance, and investors faced uncertainty about competition, valuations, future demand and the sustainability of growth.
The lesson: Individual stocks can create significant wealth, but choosing the eventual winner beforehand is difficult. Investors should not assume that yesterday’s exceptional performer will deliver similar returns in the future.
Real Case Study 2: Kodak and the Risk of Business Disruption
Eastman Kodak became widely known for its photography products and film business. Yet the transition from traditional film photography to digital imaging changed the industry’s economics.
Kodak itself had developed digital photography technology, but successfully adapting an established business model to a changing market proved challenging. The company filed for Chapter 11 bankruptcy protection in 2012 and later restructured its operations.
Kodak’s history is more complicated than a simple story of a company ignoring digital technology. Nevertheless, it illustrates how technological change can undermine a once-dominant business.
An investor who concentrated heavily in Kodak without accounting for changing industry economics could have suffered significant losses.
A diversified ETF holding many unrelated companies would generally have had less direct exposure to this single company’s difficulties, although its value could still decline with the wider market.
Source: Kodak’s official photography history.
The lesson: A famous brand, a long history and past success do not guarantee future investment returns.
Real Case Study 3: Nokia and the Smartphone Transition
Nokia was a major mobile phone manufacturer before smartphones transformed the industry. The rise of competing smartphone platforms placed significant pressure on its devices business.
In its 2011 reporting, Nokia documented a 25% decline in smart-device volumes compared with 2010, alongside a 27% decline in smart-device net sales.
These figures illustrate how quickly a company’s competitive position can change when customers and technology move in a different direction.
Nokia’s later business and corporate structure evolved, so its history should not be interpreted as a claim that every Nokia investment necessarily became worthless.
The lesson: Individual stock investors must monitor whether a company’s competitive advantage is weakening. A diversified ETF can reduce the damage caused by one company’s decline, although it cannot eliminate broad market risk.
Source: Nokia’s 2011 reporting.
Real Case Study 4: Why Beating the Market Is Difficult
The challenge of stock selection is not limited to individual investors. Professional investment managers also struggle to outperform their benchmarks consistently.
S&P Dow Jones Indices’ SPIVA U.S. Year-End 2025 report, published in March 2026, found that 79% of active large-cap US equity funds underperformed the S&P 500 during 2025. The report also found that approximately 89% underperformed over the preceding 15-year period.
These statistics concern actively managed funds, not every individual stock investor. They also refer to a specific market, benchmark and measurement period. They should not be interpreted as proof that no investor can beat an index.
Nevertheless, they demonstrate how difficult sustained outperformance can be, even for professional managers.
The lesson: A low-cost index ETF can be a sensible foundation for investors who do not have the time, skills or desire to research individual companies continuously.
Individual Stocks vs ETFs: How Returns and Risk Differ
The return from an individual stock depends heavily on the company’s performance and the price paid for its shares. ETF returns depend on the underlying portfolio, its weighting methodology, expenses and the performance of its investments.
Consider two hypothetical portfolios, each starting with $10,000.
| Scenario | Portfolio A: One stock | Portfolio B: Diversified ETF |
|---|---|---|
| Initial investment | $10,000 | $10,000 |
| Illustrative return | -40% | -15% |
| Value after the decline | $6,000 | $8,500 |
| Loss in dollars | $4,000 | $1,500 |
These figures are hypothetical and do not represent the actual historical performance of a particular stock or ETF. They illustrate how diversification may reduce the effect of company-specific losses, while not guaranteeing protection against market declines.
A diversified ETF can also underperform an individual stock during a strong rally. There is no rule requiring the ETF to produce the higher return in every period.
What Is Compound Growth, and Why Does It Matter?
Compound growth occurs when investment gains remain invested and can generate further gains. Over long periods, this process can substantially increase the value of a portfolio.
For example, suppose an investor contributes $200 per month for 30 years. If the investment earns a hypothetical 7% annual return, compounded monthly, the future balance would be approximately $244,000.
The investor would have contributed $72,000 in total. The remainder would represent investment growth under the assumed return.
This is a mathematical illustration, not a forecast. Actual returns fluctuate, fees and taxes may reduce results, and some periods may produce losses.
The key point is that both individual stocks and ETFs can benefit from compounding. However, an ETF’s diversification may make it easier for some investors to maintain a consistent long-term strategy without relying on the success of a small number of companies. Learn more about building long-term wealth through consistent investing, diversification and disciplined financial habits.
How to Build a Portfolio Using Stocks and ETFs
Investors do not have to choose one approach exclusively. For more guidance on combining investments, read our guide to portfolio strategy and asset allocation. A portfolio can use diversified ETFs as its foundation and allocate a smaller portion to individual stocks.
For example, an investor with a long time horizon and a high tolerance for market fluctuations might consider an illustrative allocation such as:
| Investment category | Example allocation |
|---|---|
| Broad domestic equity ETF | 60% |
| International equity ETF | 20% |
| Individual stocks | 10% |
| Bond ETF or other defensive assets | 10% |
This example is not a universal recommendation. The appropriate allocation depends on financial goals, emergency savings, debt, investment horizon, tax circumstances and risk tolerance. A portfolio containing 90% equity investments may still experience substantial losses.
Investors should also check for overlapping holdings. For example, purchasing several technology stocks that are already major holdings in an S&P 500 ETF may increase concentration rather than meaningfully diversify the portfolio.
A Practical Approach for Beginners
Beginners can start by learning how broad-market ETFs work, understanding fees and identifying the level of investment risk they can tolerate.
Before buying individual stocks, they should understand basic financial statements, earnings, valuation, competitive advantages and the risks associated with a company’s industry.
If they choose to purchase individual shares, they should avoid investing money needed for near-term expenses and consider how a substantial loss would affect their overall financial situation.
How to Evaluate an Individual Stock
A structured research process helps investors avoid relying solely on excitement, headlines or social media recommendations.
Revenue growth: Is the company generating more sales over time? Are those sales sustainable?
Profitability: Are operating margins and net income improving, or is the company growing without establishing a viable business model?
Cash flow: Does the company generate cash from its operations? How much capital does it need to maintain or expand the business?
Debt: Can the company reasonably service its borrowing obligations, particularly if interest rates rise or earnings decline?
Competitive advantage: Does the company have advantages such as brand strength, switching costs, network effects or cost leadership?
Valuation: Is the stock price reasonable relative to the company’s expected earnings, cash flow and growth prospects?
Management quality: Does management communicate clearly, allocate capital responsibly and treat shareholders fairly?
No single metric guarantees success. Investors should assess these factors together and consider the possibility that their assumptions may be wrong.
How to Evaluate an ETF
ETF selection also requires research, even when the fund follows a well-known index.
Start by identifying the fund’s objective and benchmark. Confirm whether it tracks a broad market, a single sector, a bond index or a specialized investment theme.
Next, review its expense ratio, holdings, diversification, trading liquidity and tracking difference. Liquidity matters because the bid-ask spread—the difference between the price buyers offer and the price sellers request—can increase the cost of trading.
Investors should also understand the fund’s distribution policy, tax treatment and domicile. These factors can be particularly important when purchasing foreign-listed funds.
Finally, examine the ETF’s concentration and underlying risks. A fund holding many technology companies may still be vulnerable to a downturn affecting the technology sector.
Individual Stocks vs ETFs for Different Investors
Beginners
Broadly diversified, low-cost ETFs can be a useful starting point because they reduce the need to identify individual company winners. Beginners should still learn about market risk, fees, asset allocation and the possibility of losing money.
Experienced Investors
Investors with financial knowledge and the time to conduct detailed research may choose individual stocks. They should measure their performance against an appropriate benchmark after costs and taxes rather than judging success only by whether their investments made money.
Long-Term Investors
Long-term investors may benefit from a disciplined approach that spreads investments across suitable assets and avoids frequent, emotionally driven trading. Both ETFs and individual stocks can fit a long-term strategy, but concentrated portfolios require particular attention to risk.
Retirees and Investors Approaching Retirement
Investors who need to withdraw money soon may have less time to recover from a major market decline. Their portfolios may require a combination of equities, high-quality bonds, cash reserves and other appropriate assets rather than an all-stock strategy.
Age alone does not determine the correct allocation. Income needs, pension benefits, health of finances, withdrawal requirements and risk tolerance also matter.
Common Mistakes to Avoid
Buying a stock because it has already risen sharply: Past performance does not establish that a stock is attractively valued today.
Assuming ETFs cannot lose money: Equity ETFs can experience severe declines during market crashes.
Ignoring fees: Small annual expenses can accumulate over long periods and reduce net returns.
Confusing diversification with owning many funds: Several ETFs may hold the same companies, creating hidden concentration.
Trading too frequently: Repeated transactions can increase costs, taxes and emotional mistakes.
Investing without an emergency fund: Money needed for rent, medical costs or other near-term obligations should not depend on volatile investments.
Ignoring taxes and currency risk: Investors buying foreign assets should understand local tax rules, currency movements and brokerage charges.
Frequently Asked Questions About Individual Stocks vs ETFs
1. Are individual stocks better than ETFs?
Neither is always better. Individual stocks may outperform substantially, but they can also lose considerable value. Diversified ETFs reduce dependence on a single company and may be easier to manage for long-term investors.
2. Are ETFs safer than individual stocks?
Broadly diversified ETFs generally reduce company-specific risk. However, they remain exposed to market risk, and concentrated or leveraged ETFs can be particularly risky.
3. Can individual stocks outperform an S&P 500 ETF?
Yes. Some individual stocks outperform the S&P 500 by a wide margin. Others underperform or lose most of their value. Identifying future winners consistently is difficult.
4. How much money do I need to start investing in ETFs?
The minimum depends on the fund’s share price, your broker and whether fractional shares are available. Some platforms permit small investments, while others require purchasing whole shares.
5. Should beginners buy stocks or ETFs first?
Many beginners find diversified ETFs easier to understand and maintain. Learning about diversification, fees and market risk before selecting individual stocks can help establish a stronger investment foundation.
6. Can I own individual stocks and ETFs together?
Yes. Some investors use diversified ETFs as their core portfolio and individual stocks for additional exposure to selected companies. The combined portfolio should be assessed for overlap and concentration risk.
7. Do ETFs pay dividends?
Some ETFs distribute income received from their underlying investments. The amount and frequency depend on the fund’s holdings and distribution policy. Distributions are not guaranteed and may have tax consequences.
8. Do individual stocks have lower fees than ETFs?
Individual stocks generally do not charge an annual fund expense ratio, but trading costs, bid-ask spreads, account charges and taxes may apply. ETFs have operating expenses in addition to any applicable trading costs.
9. Should I sell my stocks when the market crashes?
A market decline alone does not determine whether selling is appropriate. Investors should reassess their financial needs, diversification, original investment reasoning and ability to tolerate further losses. Avoid making decisions solely from panic or fear.
10. Which strategy is better for long-term wealth building?
For investors who prefer simplicity and broad diversification, a low-cost ETF strategy can be a practical option. Investors with the knowledge, discipline and time to research businesses may also choose individual stocks. In either case, costs, diversification, suitable risk levels and consistent behaviour matter.
Final Verdict: Should You Buy Individual Stocks or Stick to ETFs?
The choice between individual stocks and ETFs is ultimately a decision about how you want to manage investment risk, research and portfolio maintenance.
Individual stocks offer direct exposure to businesses and the possibility of exceptional returns. They also require investors to accept company-specific uncertainty and the possibility of substantial losses.
ETFs offer a convenient way to access diversified portfolios, often with relatively low expenses. Broad-market ETFs can reduce dependence on individual companies, but they cannot eliminate stock market risk or guarantee positive returns.
For many investors, a diversified ETF portfolio can provide a straightforward foundation for long-term wealth building. Those who want to select individual companies may choose to do so with a carefully limited allocation and a disciplined research process.
The most suitable approach is the one that fits your financial circumstances, risk tolerance and time horizon, and that you can follow consistently through both rising and falling markets.
Financial disclaimer: This article is for educational and informational purposes only. It does not constitute personalized financial, investment or tax advice. Investments can lose value, and past performance does not guarantee future results. Consider your circumstances and consult a qualified financial professional when appropriate.